Business Tax Planning Guide: Corporate Tax Rules, Financial Records, Compliance Factors, and Planning Insights
Business tax planning involves organizing financial information, understanding applicable tax obligations, maintaining appropriate records, and evaluating business decisions in light of current tax rules.
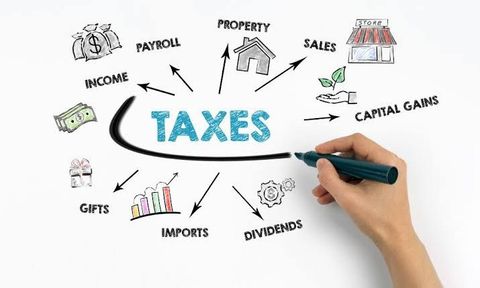
For U.S. businesses, tax responsibilities depend heavily on the organization's structure. The IRS identifies income tax, estimated taxes, self-employment tax, employment taxes, and excise tax among the major categories of business taxes.
Effective planning is not simply about reducing taxes. It also involves maintaining accurate records, meeting filing and payment requirements, documenting business expenses, and understanding how transactions may affect taxable income.
Why Business Tax Planning Matters
A structured tax-planning process can help businesses:
Organize financial records
Monitor taxable income
Track potentially deductible expenses
Prepare accurate tax returns
Plan estimated tax payments
Review cash-flow requirements
Document business transactions
Identify applicable credits and deductions
Coordinate tax planning with financial decisions
Reduce the risk of incomplete or unsupported tax reporting
The IRS notes that good business records can help prepare financial statements, identify income sources, track deductible expenses, prepare tax returns, and support amounts reported on those returns.
Business Structure and Tax Treatment
The legal and tax structure of a business affects how income and tax responsibilities are reported.
Common structures include:
Sole proprietorships
Partnerships
S corporations
C corporations
Limited liability companies
An LLC can be treated differently for federal tax purposes depending on its tax election and ownership structure. The applicable tax forms and payment responsibilities can therefore differ between businesses.
Businesses should distinguish between their legal structure and their federal tax classification because the two concepts do not always operate identically.
Major Business Tax Categories
Federal Income Tax
Businesses generally have federal income-tax responsibilities, although the reporting method depends on the business structure.
The IRS explains that most businesses must file an annual income-tax return, while partnerships generally file an information return rather than paying federal income tax at the partnership level.
Estimated Taxes
Businesses and business owners may need to make tax payments during the year rather than waiting until the annual return.
The IRS generally states that individuals such as sole proprietors, partners, and S corporation shareholders may need estimated tax payments when they expect to owe at least $1,000 when filing. Corporations generally must make estimated payments when they expect to owe at least $500.
Estimated-tax calculations should be updated when income, deductions, credits, or applicable tax rules change.
Employment Taxes
Businesses with employees may have obligations involving:
Federal income-tax withholding
Social Security and Medicare taxes
Federal unemployment taxes
Payroll records
Employment tax reporting
Information returns
Employment-tax requirements should be reviewed separately from the organization's income-tax planning.
Excise Taxes
Certain industries, products, transactions, or activities can create federal excise-tax obligations.
The applicable requirements depend on the business activity and transaction.
Financial Records for Tax Planning
Accurate financial records are central to business tax planning.
A recordkeeping system may include:
Income records
Expense records
Bank statements
Invoices
Receipts
Payroll records
Asset records
Loan documentation
Investment records
Depreciation schedules
Tax returns
Supporting documentation
The IRS states that electronic records are subject to the same general recordkeeping requirements as paper records and should provide a complete and accurate record that remains accessible.
Tracking Business Income
Businesses may receive income from multiple sources.
Records should help identify:
Customer receipts
Sales
Interest income
Investment income
Refunds
Other business receipts
Non-taxable or differently treated amounts where applicable
Separating business and nonbusiness transactions can make financial reporting and tax preparation more reliable.
Tracking Business Expenses
Businesses should maintain documentation supporting expenses reported for tax purposes.
Examples can include:
Rent
Utilities
Advertising
Insurance
Professional expenses
Employee compensation
Business travel
Equipment
Supplies
Technology
Interest
Certain depreciation-related items
Whether a particular expense is deductible depends on applicable tax rules, the nature of the expense, the business activity, and supporting documentation.
The IRS emphasizes that taxpayers generally need evidence such as receipts, canceled checks, bills, and other documentation to substantiate deductible expenses.
Accounting Methods
Tax planning can also involve the business's accounting method.
Common approaches include:
Cash method
Income and expenses are generally recognized based on when payments are received or made, subject to applicable rules.
Accrual method
Income and expenses are generally recognized according to applicable accounting and tax recognition rules rather than simply when cash changes hands.
The IRS explains that accrual-method taxpayers generally recognize income when the relevant events establish the right to receive it and the amount can be determined with reasonable accuracy. Expense treatment can depend on the applicable liability and economic-performance rules.
Businesses should evaluate accounting-method decisions with qualified tax and accounting professionals.
Tax Deductions and Credits
Tax planning may involve reviewing potentially applicable:
Business expense deductions
Depreciation
Amortization
Tax credits
Retirement-plan contributions
Certain employee-related expenses
Research-related incentives
Energy-related incentives
Other industry-specific provisions
Eligibility depends on the specific business, transaction, tax year, and applicable rules.
A tax deduction generally reduces taxable income, while a tax credit generally reduces tax liability directly. The two should not be treated as interchangeable.
Depreciation and Business Assets
Businesses that purchase or otherwise acquire qualifying assets may need to account for depreciation or other applicable capitalization rules.
Relevant records can include:
Acquisition date
Purchase documentation
Asset description
Tax basis
Improvements
Depreciation method
Disposition information
The IRS notes that basis information can be important for calculating gain or loss and for depreciation, amortization, depletion, and certain casualty-loss calculations.
Tax Planning and Cash Flow
Tax obligations should be incorporated into broader cash-flow planning.
Businesses can monitor:
Revenue → Expenses → Taxable Income → Estimated Tax → Available Cash
A profitable business can still experience cash-flow pressure if tax obligations are not incorporated into financial forecasts.
Tax planning can therefore be coordinated with:
Budgeting
Capital expenditures
Payroll planning
Debt payments
Inventory planning
Cash reserves
Business expansion
Investment decisions
Corporate Tax Compliance
Compliance involves more than filing an annual return.
Organizations may need to monitor:
Filing deadlines
Estimated payment deadlines
Information returns
Payroll reporting
State taxes
Local taxes
Sales or use taxes
Excise taxes
Tax registrations
Record-retention requirements
Federal requirements are only one part of the compliance picture. State and local obligations can differ substantially.
2026 Tax Planning Considerations
Tax rules can change from year to year. The IRS has published tax-year 2026 inflation adjustments and other provisions affecting 2026 tax planning.
The IRS also continues updating its electronic filing systems and tax forms for tax year 2026, including business return schemas and related filing infrastructure.
Businesses should therefore verify current tax-year requirements rather than relying on prior-year assumptions.
IRS Business Tax Account
Digital tax administration is also becoming more accessible.
In April 2026, the IRS announced an expansion of Business Tax Account access to partnerships, government entities, and tax-exempt organizations. Eligible users can use the platform for activities such as viewing tax balances, making payments, accessing certain notices and transcripts, and requesting a tax compliance check.
Businesses should use official IRS resources when checking account information and current federal tax requirements.
Tax Planning and Financial Statements
Financial statements provide an important foundation for tax planning.
Businesses commonly review:
| Financial Information | Planning Purpose |
|---|---|
| Income statement | Reviews revenue and expenses |
| Balance sheet | Reviews assets, liabilities, and equity |
| Cash-flow statement | Evaluates liquidity |
| General ledger | Supports transaction analysis |
| Accounts receivable | Reviews outstanding customer balances |
| Accounts payable | Tracks business obligations |
| Fixed-asset schedule | Supports asset and depreciation analysis |
The IRS notes that reliable records support both financial statements and tax returns.
Tax Recordkeeping
There is no single retention period that applies to every business document.
The appropriate period can depend on the document, transaction, tax return, employment-tax requirement, and applicable law.
The IRS explains that records should generally be kept as long as needed to substantiate income and deductions. Employment-tax records generally need to be retained for at least four years.
Businesses should also consider longer retention requirements that may arise from state law, contracts, litigation, property records, or other obligations.
Business Tax Planning Checklist
Organizations can periodically review:
Confirm business tax classification
Review federal tax obligations
Review state and local tax requirements
Track business income
Document business expenses
Reconcile financial accounts
Review estimated tax requirements
Maintain payroll records
Review asset and depreciation records
Monitor applicable tax credits
Review filing deadlines
Maintain supporting documentation
Review tax-law changes
Coordinate tax planning with cash-flow forecasts
Consult qualified tax and accounting professionals
Tools and Resources
Useful resources for business tax planning include:
IRS Business Taxes: Federal business-tax information and filing guidance.
IRS Publication 583: Starting a business and keeping financial records.
IRS Publication 334: Small-business tax information.
IRS Business Tax Account: Digital access to eligible business tax information.
Accounting software: Helps organize transactions, income, expenses, and financial reports.
Payroll systems: Help maintain employee compensation and employment-tax records.
Document-management systems: Help organize supporting tax documentation.
Financial reporting systems: Support income statements, balance sheets, and cash-flow analysis.
Frequently Asked Questions
What is business tax planning?
Business tax planning is the process of organizing financial information and evaluating business decisions in light of applicable tax rules, deductions, credits, filing requirements, and payment obligations.
What records should a business keep for taxes?
Businesses generally need records that support income, expenses, deductions, credits, assets, and other amounts reported on tax returns. The appropriate records depend on the business and transaction.
Do corporations have to make estimated tax payments?
Generally, corporations may need to make estimated payments if they expect to owe at least $500 when filing their federal return. Specific rules and exceptions can apply.
Why are financial records important for tax planning?
Financial records help businesses track income and expenses, prepare financial statements, support tax returns, and substantiate amounts reported to tax authorities.
Do business tax rules change every year?
Tax rules can change through legislation, regulations, administrative guidance, and annual inflation adjustments. Businesses should verify current requirements for each tax year rather than relying exclusively on prior-year information.
Conclusion
Business tax planning connects corporate tax rules, financial records, cash-flow management, tax compliance, and broader financial planning.
A strong planning process begins with accurate transaction records and continues through expense documentation, estimated-tax analysis, financial reporting, filing preparation, and regular review of tax-law changes.
Because tax treatment depends on business structure, transaction details, jurisdiction, and tax year, significant tax decisions should be based on current official guidance and advice from appropriately qualified tax and accounting professionals.
Related Post...