Trust Planning Guide: Estate Documents, Asset Management, Legal Information, and Family Planning Insights
Trust planning is an estate-planning process that can help organize assets, establish instructions for their management, and define how property may be transferred to beneficiaries.
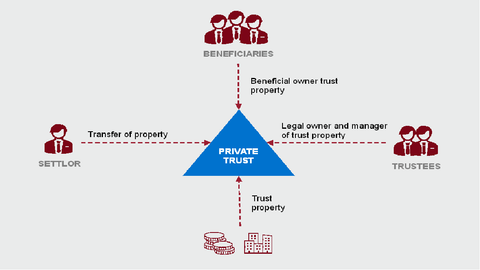
A trust is a legal arrangement in which a trustee manages property for one or more beneficiaries according to the terms established by the trust document.
Trust planning can involve financial accounts, real estate, business interests, investments, personal property, and other assets. The appropriate structure depends on the individual's goals, assets, family circumstances, jurisdiction, and applicable law.
Why Trust Planning Matters
A properly structured trust can address more than the eventual transfer of property.
Trust planning may be considered for:
Managing assets during a person's lifetime
Establishing instructions for beneficiaries
Planning for incapacity
Organizing family wealth
Addressing minor beneficiaries
Coordinating business interests
Supporting charitable objectives
Addressing certain estate-tax considerations
Establishing continuity of asset management
Potentially reducing the role of probate for assets properly transferred to a trust
Trusts do not automatically provide every desired legal or tax result. Their effects depend on the trust structure, funding, administration, applicable law, and individual circumstances.
What Is a Trust?
A trust generally involves three primary roles:
Grantor or Settlor: The person who creates the trust and transfers property into it.
Trustee: The person or institution responsible for managing trust property according to the trust document.
Beneficiary: The person or organization entitled to receive benefits from the trust according to its terms.
Some trusts can be changed or revoked by the person who created them, while others are structured to become difficult or impossible to change after creation.
The legal consequences can differ substantially between these structures.
Common Types of Trusts
Revocable Living Trust
A revocable living trust can generally be changed or revoked by the grantor during the grantor's lifetime, subject to the terms of the trust and applicable law.
It is often used as part of broader estate administration and asset-management planning.
Irrevocable Trust
An irrevocable trust generally places greater restrictions on the grantor's ability to change or revoke the arrangement.
Depending on its structure, an irrevocable trust may have different tax, asset-management, and estate-planning consequences from a revocable trust.
Testamentary Trust
A testamentary trust is established through a will and generally becomes effective after the relevant estate process occurs.
It can provide instructions for managing assets for beneficiaries after death.
Special Needs Trust
Certain trusts can be structured to hold assets for a beneficiary with a disability while addressing applicable benefit-program rules.
Because public-benefit eligibility can be highly technical, specialized legal guidance is important when this type of trust is being considered.
Charitable Trust
Certain charitable trust structures can be used to support charitable objectives while also producing specific legal or tax consequences.
The tax treatment depends on the structure and applicable federal and state rules.
Trusts and Estate Documents
Trust planning generally works best when coordinated with other estate documents.
Important documents may include:
Will
Trust agreement
Financial power of attorney
Healthcare directive
Beneficiary designations
Property records
Business succession documents
Guardianship provisions where appropriate
Digital-asset instructions
A pour-over will, for example, can work alongside a revocable trust by addressing certain assets that were not transferred into the trust during the grantor's lifetime.
The precise effect depends on state law and the wording of the documents.
Funding a Trust
Creating a trust document is only one part of trust planning.
A trust may need to be funded, meaning ownership of appropriate assets is transferred or otherwise coordinated with the trust structure.
Potential trust assets can include:
Bank accounts
Investment accounts
Real estate
Business interests
Certain personal property
Other assets permitted under the trust arrangement
Some assets may instead be coordinated through beneficiary designations or other estate-planning mechanisms.
Failure to properly coordinate ownership can affect how an asset is handled after death or during incapacity.
Beneficiary Planning
Beneficiary designations can play an important role in estate planning.
They may apply to:
Retirement accounts
Life insurance
Certain investment accounts
Bank accounts
Transfer-on-death arrangements
Other accounts with designated beneficiaries
Beneficiary designations should be reviewed alongside trust documents and wills.
A beneficiary designation can sometimes control the transfer of an asset independently of a will, depending on the account and applicable law.
Trusts and Asset Management
Trustees may have responsibility for managing trust property according to the trust document and applicable fiduciary requirements.
Trust administration can involve:
Maintaining financial records
Managing investments
Paying appropriate expenses
Maintaining property
Distributing assets
Communicating with beneficiaries
Preparing required tax documents
Maintaining documentation
Following trust instructions
Trustee responsibilities vary according to the trust document, state law, asset types, and circumstances.
Professional trustees and other qualified professionals may be involved when trust administration is complex.
Family Planning and Trusts
Trust planning can be especially relevant when multiple generations are involved.
Families may use estate documents to establish instructions concerning:
Children
Grandchildren
Family businesses
Real estate
Investment assets
Education-related expenses
Beneficiary distributions
Family governance
Charitable goals
A trust can also establish conditions or timing for certain distributions when permitted under applicable law.
The language should be sufficiently clear to reduce uncertainty about the trustee's responsibilities and beneficiary rights.
Trusts and Business Ownership
Business owners may need to coordinate estate documents with ownership structures.
Relevant considerations can include:
Ownership interests
Buy-sell agreements
Business succession
Voting rights
Management continuity
Valuation provisions
Insurance arrangements
Partnership or operating agreements
A trust does not automatically replace a business succession plan. Business documents and estate documents should be reviewed together to identify potential conflicts.
Trusts and Tax Planning
Trusts can have significant tax implications.
Potential areas include:
Federal estate tax
Federal gift tax
Generation-skipping transfer tax
Income tax
State estate taxes
State inheritance taxes
Property-related taxes
The tax treatment depends heavily on the trust structure, asset ownership, beneficiary relationships, timing, and applicable federal and state rules.
Tax provisions can change, so current professional guidance is important for significant estate-planning decisions.
Probate and Trust Planning
Probate is the court-supervised process used in many jurisdictions to administer certain assets after death.
Assets properly transferred to a trust may be administered through the trust rather than passing through probate, depending on the asset and jurisdiction.
However, creating a trust does not necessarily eliminate probate for every asset.
Assets that remain outside the trust may still require probate unless another transfer mechanism applies.
Trustee Selection
Choosing a trustee is an important part of trust planning.
Potential trustees can include:
Family members
Friends
Professional fiduciaries
Financial institutions
Other qualified individuals or organizations
Important considerations may include:
Reliability
Understanding of fiduciary responsibilities
Financial organization
Impartiality
Ability to communicate
Availability over the expected trust duration
Potential conflicts of interest
The trust document can also establish successor-trustee provisions.
Digital Assets and Trust Planning
Modern estate planning can include digital property and online accounts.
Examples include:
Digital financial accounts
Online investment platforms
Digital photographs
Domain names
Business accounts
Cloud-stored records
Cryptocurrency or other digital assets
Access to digital assets can be governed by platform agreements, privacy rules, state laws, and federal laws.
Estate documents should therefore address digital assets where appropriate and should not simply rely on informal account-password sharing.
Trust Administration After Death
When a trust becomes irrevocable or enters an administration period after the grantor's death, the trustee may have substantial responsibilities.
These can include:
Reviewing the trust document
Identifying trust assets
Obtaining appropriate valuations
Notifying beneficiaries where required
Paying valid expenses and obligations
Preparing required tax filings
Managing or liquidating assets as authorized
Making distributions according to the trust
Maintaining records
Completing the administration process
The exact requirements vary according to the trust and applicable state law.
Recent Developments in Trust Planning
Estate planning continues to evolve alongside changes in tax rules, digital assets, financial products, and family structures.
Important areas to monitor include:
Changes to federal estate and gift-tax thresholds
State estate and inheritance-tax developments
Digital-asset planning
Online estate-document platforms
Electronic document execution
Changes involving retirement-account beneficiaries
Trust administration technology
Increased attention to fiduciary recordkeeping
Business succession planning for closely held companies
Tax and estate laws can change over time, so older estate documents may not always reflect current circumstances or applicable rules.
Laws, Policies, and Compliance
Trust planning in the United States can involve federal and state legal requirements.
Relevant areas may include:
State trust law
State probate law
Federal estate-tax rules
Federal gift-tax rules
Generation-skipping transfer-tax rules
Fiduciary duties
Property law
Retirement-account rules
Life-insurance beneficiary rules
Digital-asset laws
State-specific inheritance requirements
The Internal Revenue Service provides federal information concerning estate and gift taxes, while state statutes determine many aspects of trust administration and inheritance.
Because trust law varies considerably between states, a trust created under one state's laws may have different administration requirements from one governed by another state's law.
Trust Planning Checklist
Before establishing or reviewing a trust plan, consider:
Define the purpose of the trust
Identify intended beneficiaries
Review current assets
Identify assets that may be transferred to the trust
Review beneficiary designations
Select a trustee and successor trustee
Coordinate the trust with a will
Review powers of attorney
Review healthcare documents
Consider business ownership
Review potential tax consequences
Address digital assets
Review property ownership
Document important family instructions
Review the plan periodically
Tools and Resources
Useful U.S. resources include:
Internal Revenue Service: Federal estate, gift, and trust tax information.
State courts: Probate and trust-administration information.
State statutes: Applicable trust, inheritance, and property laws.
Qualified estate-planning attorneys: Legal guidance concerning trust structures and documents.
Tax professionals: Guidance concerning applicable tax treatment.
Financial professionals: Assistance with investment and asset-management considerations.
Professional fiduciaries: Potential trustee or trust-administration resources.
Frequently Asked Questions
What is trust planning?
Trust planning is the process of determining whether a trust may be useful, selecting an appropriate structure, identifying beneficiaries, preparing trust documents, coordinating assets, and establishing an administration plan.
What is the difference between a revocable and irrevocable trust?
A revocable trust can generally be changed or revoked under its terms, while an irrevocable trust generally places greater restrictions on modification or revocation. Their tax and legal consequences can also differ.
Does a trust avoid probate?
Assets properly transferred to a trust may avoid probate in some circumstances, but a trust does not automatically prevent probate for every asset. Ownership and applicable state law matter.
Who manages assets in a trust?
The trustee manages trust property according to the trust document and applicable fiduciary requirements.
Should a trust be reviewed periodically?
Yes. Major changes in family circumstances, assets, residence, business ownership, tax law, beneficiary relationships, or personal objectives can justify an estate-plan review.
Conclusion
Trust planning can provide a structured framework for managing assets, establishing beneficiary instructions, and coordinating broader estate documents.
A comprehensive plan may involve trusts, wills, beneficiary designations, powers of attorney, healthcare documents, business succession arrangements, and digital-asset planning.
Because trust law, tax rules, and probate procedures vary by jurisdiction and can change over time, significant estate-planning decisions should be based on current information and appropriately qualified professional guidance.
Related Post...
Home Automation Basics Guide: Explanation, Key Information, Useful Tips, and Smart Home Insights
Updated: January 06, 2026
Read More
Estate Planning Basics Guide: Legal Documents, Asset Protection, Family Insights, and Practical Tips
Updated: September 23, 2026
Read More