Inheritance Planning Guide: Beneficiary Decisions, Estate Documents, Tax Factors, and Practical Tips
Inheritance planning is the process of organizing how assets, property, financial accounts, and other interests may transfer to family members or other beneficiaries after death.
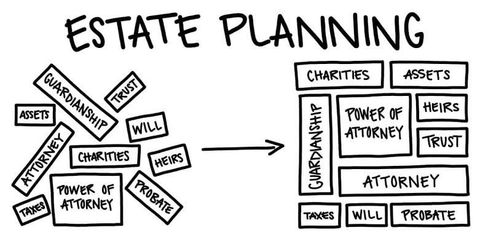
A well-organized inheritance plan can bring together wills, trusts, beneficiary designations, property ownership, financial accounts, insurance arrangements, tax considerations, and important personal records.
The appropriate approach depends on the type and value of assets, family circumstances, state law, existing estate documents, and the individual's broader estate-planning objectives.
Why Inheritance Planning Matters
Inheritance planning can help clarify who is intended to receive particular assets and how those assets are expected to transfer.
Planning may address:
Beneficiary designations
Wills and trusts
Retirement accounts
Life insurance proceeds
Bank and investment accounts
Real estate
Business interests
Personal property
Digital assets
Estate taxes
Income-tax considerations
Potential probate procedures
Family communication
Estate administration
Some assets can pass through beneficiary designations or ownership arrangements outside the probate process, while other assets may be distributed according to a will or applicable state law.
Beneficiary Decisions
Beneficiary designations are an important part of inheritance planning because certain financial accounts and insurance policies can transfer directly to named beneficiaries.
Common examples include:
Retirement accounts
Life insurance policies
Certain bank accounts
Certain investment accounts
Transfer-on-death arrangements
Beneficiary information should be reviewed periodically, particularly after major life events such as marriage, divorce, the birth of a child, or the death of a named beneficiary.
It is also important to distinguish between primary beneficiaries and contingent beneficiaries. A contingent beneficiary may receive the asset if the primary beneficiary cannot or does not receive it.
Beneficiary designations should generally be coordinated with the rest of the estate plan rather than treated as isolated documents.
Wills and Estate Documents
A will can identify intended beneficiaries and provide instructions concerning the distribution of assets that are subject to the will.
An estate plan may also include:
Revocable living trusts
Irrevocable trusts
Financial powers of attorney
Healthcare directives
Beneficiary designation forms
Property ownership documents
Business succession documents
Digital-asset instructions
Guardianship provisions where applicable
The appropriate documents depend on the individual's circumstances and applicable state law.
An estate plan should also be reviewed periodically because outdated documents can create administrative or distribution issues.
Trusts and Inheritance Planning
Trusts can be used for different estate-planning purposes.
Depending on the structure, a trust may help address:
Asset management
Distribution timing
Beneficiary protections
Privacy considerations
Management of assets for minors
Special family circumstances
Business or property interests
Certain tax-planning objectives
A trust does not automatically produce a particular tax result or eliminate all estate-administration requirements. The legal and tax consequences depend on the trust terms, assets, parties, and applicable law.
Real Estate and Inherited Property
Real estate can create additional inheritance-planning considerations.
Planning may involve:
Ownership structure
Joint ownership
Transfer provisions
Mortgage obligations
Property taxes
Insurance
Maintenance responsibilities
Appraisals
Rental-property interests
Future sale or transfer
For U.S. federal income-tax purposes, inherited property generally receives a basis equal to its fair market value at the date of death, subject to specific rules and exceptions. If inherited property is later sold, the difference between the property's adjusted basis and its sale price can affect taxable gain or loss.
Because state inheritance and property-tax rules can differ, real estate should be reviewed in the context of the applicable state and the estate's overall structure.
Retirement Accounts and Inheritance
Retirement accounts require particular attention because beneficiary designations and post-death distribution rules can affect how inherited assets are handled.
Planning may involve:
Primary and contingent beneficiaries
Spousal versus non-spousal beneficiaries
Required distributions
Account types
Taxable versus tax-deferred assets
Estate-planning objectives
Current IRS rules
Retirement-account inheritance rules can be complex and can depend on the type of account, the beneficiary's relationship to the deceased owner, and other circumstances.
Beneficiaries should review current IRS requirements before making distribution decisions.
Life Insurance and Beneficiary Planning
Life insurance can provide funds to designated beneficiaries after the insured person's death.
Important planning considerations can include:
Primary beneficiaries
Contingent beneficiaries
Ownership of the policy
Policy documentation
Beneficiary ages
Trust ownership
Coordination with the broader estate plan
State-specific requirements
Beneficiary forms should be kept current and coordinated with other estate documents.
Federal Estate Tax Factors
Federal estate tax is imposed on certain estates rather than automatically on every inheritance.
For people who die in 2026, the federal basic exclusion amount is $15 million. The IRS states that Form 706 generally must be filed for a U.S. citizen or resident decedent when the gross estate, adjusted taxable gifts, and specific exemption exceed $15 million, although other filing circumstances can apply, including certain portability elections.
Estate-tax rules can change, and federal estate tax is only one part of the overall tax analysis.
State-level estate or inheritance taxes may also apply depending on where the decedent lived, where property is located, and other state-specific factors.
Inherited Property and Income Taxes
Receiving an inheritance is not necessarily the same as receiving taxable income.
For example, inherited property generally receives a tax basis tied to its fair market value at death under federal rules. If a beneficiary later sells the property for more than the applicable basis, the resulting gain may be subject to income tax.
Other inherited assets can have different tax treatment.
Potential considerations include:
Capital gains
Interest income
Dividends
Retirement-account distributions
Rental income
Business income
State income taxes
Tax treatment should therefore be evaluated asset by asset rather than assuming every inherited asset follows the same rule.
Estate Documents and Asset Inventory
An inheritance plan is easier to administer when important information can be located.
An asset inventory may identify:
| Asset Category | Information to Record |
|---|---|
| Bank accounts | Institution, account type, ownership |
| Investments | Account type, institution, ownership |
| Retirement accounts | Account type and beneficiary information |
| Life insurance | Policy details and beneficiaries |
| Real estate | Ownership, location, mortgage information |
| Business interests | Entity, ownership percentage, governing documents |
| Personal property | Important items and intended recipients |
| Digital assets | Relevant accounts and access instructions |
| Trusts | Trustee, beneficiaries, and trust documents |
Sensitive credentials should not simply be placed in an unsecured document. Appropriate security and access procedures should be considered.
Family and Beneficiary Communication
Inheritance planning can involve difficult family decisions.
Clear communication may help reduce uncertainty about:
Who is responsible for administration
Where important documents are located
Who should contact professional advisers
How property should be managed
What happens to business interests
How certain personal assets are intended to be handled
Communication should be approached carefully because family circumstances and legal rights can differ.
The goal is not necessarily to disclose every detail, but to make sure the appropriate people know where critical information and documents can be found.
Digital Assets
Modern estates can contain substantial digital property and information.
Examples include:
Online financial accounts
Digital photographs
Cloud storage
Domain names
Cryptocurrency
Online business accounts
Intellectual property
Subscription accounts
Social-media accounts
Digital-asset planning should consider applicable laws, account agreements, privacy rules, and access requirements.
Instructions should also distinguish between assets that have financial value and accounts that primarily contain personal information.
Business Interests and Inheritance
Business ownership can create additional estate-planning issues.
Planning may involve:
Ownership percentages
Operating agreements
Shareholder agreements
Buy-sell agreements
Valuation provisions
Successor ownership
Management rights
Life insurance arrangements
Transfer restrictions
A business interest should not be treated like an ordinary personal asset if the governing documents impose restrictions on transfers.
Recent Developments and 2026 Considerations
Federal estate-tax planning has an important 2026 development: the IRS currently lists a $15 million basic exclusion amount for deaths in 2026, compared with $13.99 million for deaths in 2025.
The IRS also continues to emphasize consistent basis reporting for certain inherited property. When applicable, an executor may provide beneficiaries with Schedule A of Form 8971 showing the estate-tax value used for basis purposes.
Because tax rules and state laws can change, inheritance plans should be reviewed periodically rather than relying indefinitely on rules that applied when documents were originally created.
Inheritance Planning Checklist
Before finalizing or reviewing an inheritance plan, consider:
Create or review a current will
Review trust documents where applicable
Review primary beneficiaries
Review contingent beneficiaries
Check retirement-account beneficiaries
Check life-insurance beneficiaries
Review ownership of major assets
Create an updated asset inventory
Identify important real-estate documents
Review business ownership documents
Organize important estate records
Review potential federal estate-tax exposure
Review applicable state inheritance or estate taxes
Consider the tax basis of inherited property
Document important digital assets
Identify appropriate estate professionals
Review the plan after major life events
Tools and Resources
Useful U.S. resources for inheritance planning include:
IRS estate and gift tax resources — current federal estate-tax rules, forms, thresholds, and guidance.
IRS Publication 551 — information about the basis of inherited assets.
IRS Publication 559 — information for survivors, executors, and administrators.
Form 706 instructions — current federal estate-tax filing information and 2026 thresholds.
State tax authorities — information about applicable estate, inheritance, and property-tax rules.
Estate-planning professionals — legal and tax guidance for situation-specific planning.
Frequently Asked Questions
What is inheritance planning?
Inheritance planning is the process of organizing assets, beneficiaries, estate documents, ownership arrangements, and tax considerations so property can be transferred according to the individual's estate-planning objectives.
Do beneficiaries always pay tax on an inheritance?
No. Federal tax treatment depends on the type of asset and circumstances. An inheritance is not automatically treated as ordinary taxable income, although later income, gains, or distributions from inherited assets may have tax consequences.
Should beneficiary designations be included in an estate plan?
Yes. Beneficiary designations for accounts such as retirement plans and insurance policies can affect who receives those assets and should generally be coordinated with the overall estate plan.
What happens to the tax basis of inherited property?
Inherited property generally receives a federal tax basis equal to its fair market value at the date of death, subject to specific rules and exceptions.
How often should an inheritance plan be reviewed?
There is no universal interval. A review is especially useful after marriage, divorce, a birth or death in the family, major asset changes, business changes, relocation, or significant changes in tax or estate law.
Conclusion
Inheritance planning brings together beneficiary decisions, estate documents, asset ownership, tax considerations, family communication, and practical recordkeeping.
A useful plan should account for the way different assets transfer and should coordinate wills, trusts, beneficiary designations, property ownership, retirement accounts, insurance policies, and business interests.
Federal estate-tax rules and the tax treatment of inherited assets can also affect planning. For 2026, the federal basic exclusion amount is $15 million for applicable decedents, while inherited property generally receives a federal basis tied to fair market value at death, subject to exceptions.
Because inheritance and estate rules vary by state and individual circumstances, significant planning decisions should be based on current information and advice from appropriately qualified legal and tax professionals.
Related Post...
Estate Administration Guide: Probate Processes, Asset Distribution, Legal Documents, and Family Insights
Updated: September 30, 2026
Read More
Marital Property Guide: Asset Division, Financial Decisions, Legal Rules, and Planning Insights
Updated: September 30, 2026
Read More
Living Trust Guide: Estate Documents, Asset Management, Beneficiary Planning, and Practical Tips
Updated: September 28, 2026
Read More