Corporate Governance Guide: Board Oversight, Shareholder Matters, Compliance Duties, and Business Insights
Corporate governance is the framework through which a company is directed, overseen, and held accountable.
It can establish how directors, officers, shareholders, committees, and management interact and how important decisions are reviewed.
Corporate governance may address:
Board responsibilities
Shareholder rights
Executive oversight
Corporate records
Financial reporting
Risk management
Compliance
Internal controls
Conflicts of interest
Corporate policies
Strategic oversight
The appropriate governance structure depends on the company's legal form, ownership, size, industry, jurisdiction, governing documents, and applicable laws.
Why Corporate Governance Matters
Effective governance can help establish clear responsibilities and decision-making procedures.
A governance framework can help organizations:
Define board responsibilities
Establish management oversight
Protect shareholder interests
Monitor financial reporting
Address conflicts of interest
Review major business risks
Maintain corporate records
Support regulatory compliance
Establish accountability
Improve strategic oversight
Governance is not limited to public companies. Private corporations, family businesses, nonprofits, and other organizations can also establish governance structures appropriate to their circumstances.
Corporate Governance Structure
A typical corporation may involve several distinct roles.
Shareholders
Shareholders generally hold ownership interests and may have voting rights established by corporate documents and applicable law.
Board of Directors
The board provides oversight and generally supervises major strategic and organizational matters.
Officers and Management
Executives and managers typically handle day-to-day operations subject to the company's governance structure and applicable authority.
Committees
Larger organizations may establish committees for areas such as audit, compensation, governance, risk, or other specialized responsibilities.
The precise allocation of authority varies by entity type, governing documents, and jurisdiction.
Board Oversight
Board oversight can involve both strategic and monitoring responsibilities.
Board activities may include:
Reviewing corporate strategy
Monitoring financial performance
Evaluating major risks
Reviewing significant transactions
Overseeing executive leadership
Monitoring compliance
Reviewing internal controls
Assessing business continuity
Reviewing major investments
Monitoring organizational performance
Directors generally rely on information provided by management and advisors when carrying out their responsibilities.
Board materials should provide sufficient information to support informed decision-making.
Director Duties
Director duties vary according to jurisdiction and company structure.
Potential duties can include:
Duty of care
Duty of loyalty
Oversight responsibilities
Good-faith decision-making
Avoidance or management of conflicts
Compliance with governing documents
Directors may also have responsibilities relating to financial reporting, corporate records, regulatory matters, and other areas depending on the company and applicable law.
Directors should understand the legal standards applicable to their particular role rather than relying on a generic governance framework.
Shareholder Matters
Shareholder rights and responsibilities can depend on the company's organizational documents, ownership structure, share class, and applicable law.
Shareholder matters may include:
Voting rights
Election of directors
Share transfers
Dividends or distributions
Ownership records
Shareholder meetings
Information rights
Major corporate transactions
Amendments to governing documents
Different classes of ownership interests can have different voting, economic, or other rights.
Shareholder Meetings
Shareholder meetings can provide a formal mechanism for owners to vote on matters requiring shareholder approval.
Meeting processes may involve:
Notice
Meeting materials
Voting procedures
Proxies
Quorum requirements
Resolutions
Meeting minutes
Voting records
Requirements can vary according to the entity's governing documents and applicable corporate law.
Corporate Records
Maintaining accurate corporate records is an important governance function.
Records may include:
Articles of incorporation
Bylaws
Board minutes
Shareholder minutes
Resolutions
Ownership records
Stock or membership records
Financial statements
Major contracts
Governance policies
Regulatory filings
Corporate records can provide evidence of important decisions and help demonstrate how the organization was governed.
Board Meetings and Minutes
Board meetings can be conducted regularly or when significant matters require formal consideration.
Meeting materials may include:
Financial reports
Risk reports
Compliance updates
Strategic proposals
Transaction information
Management reports
Legal updates
Technology or cybersecurity reports
Minutes should accurately document important actions and resolutions without attempting to create an unnecessary transcript of the entire meeting.
Corporate Compliance Oversight
Boards may oversee compliance frameworks without performing day-to-day compliance functions themselves.
Areas of oversight can include:
Regulatory requirements
Financial reporting
Employment obligations
Data privacy
Cybersecurity
Environmental requirements
Industry-specific rules
Internal policies
Ethics programs
The appropriate oversight model depends on the organization's size, risk profile, industry, and regulatory environment.
Internal Controls and Financial Oversight
Financial governance can include oversight of systems designed to protect organizational assets and improve the reliability of financial information.
Internal controls may address:
Authorization
Segregation of duties
Reconciliations
Access controls
Financial reporting
Expense approvals
Asset management
Recordkeeping
Audit procedures
An audit committee may have additional responsibilities in organizations where such a committee is established or required.
Risk Management
Corporate governance and enterprise risk management are closely connected.
Boards may review risks involving:
Financial performance
Legal exposure
Cybersecurity
Data privacy
Operations
Supply chains
Employees
Insurance
Reputation
Regulatory requirements
Business continuity
A board does not necessarily manage every operational risk directly. Instead, it can establish oversight mechanisms to ensure that significant risks are identified, evaluated, and addressed.
Conflicts of Interest
Conflicts can arise when a director, officer, shareholder, or other decision-maker has a personal or financial interest that could affect an organizational decision.
Governance procedures may include:
Conflict disclosures
Recusal procedures
Related-party transaction policies
Board review
Independent approval
Documentation
Organizations should establish procedures consistent with applicable law and their governing documents.
Related-Party Transactions
Transactions involving directors, officers, shareholders, family members, or affiliated entities may receive additional scrutiny.
Examples can include:
Loans
Property transactions
Consulting arrangements
Supplier relationships
Compensation arrangements
Investments
Business agreements
Organizations may establish approval and disclosure procedures to identify potential conflicts and support appropriate oversight.
Corporate Governance Policies
Governance policies can formalize expectations and responsibilities.
Examples include:
Code of conduct
Conflict-of-interest policy
Board charter
Committee charters
Whistleblower policy
Document-retention policy
Related-party transaction policy
Insider-trading policy where applicable
Risk-management policy
Information-security policy
Policies should be reviewed periodically to ensure they remain consistent with organizational practices and applicable requirements.
Compliance and Regulatory Requirements
Corporate governance can intersect with federal, state, and local requirements.
Depending on the company, relevant areas may include:
Corporate filing requirements
Securities regulation
Financial reporting
Tax obligations
Employment law
Environmental requirements
Data-protection rules
Industry-specific regulation
Public companies can have additional disclosure and reporting obligations under federal securities laws.
The SEC provides resources concerning corporate reporting, disclosure, governance-related matters, and public-company obligations. (sec.gov)
Governance and Corporate Transactions
Major transactions often require governance oversight.
These can include:
Acquisitions
Mergers
Asset transactions
Equity transactions
Major financing arrangements
Significant investments
Related-party transactions
Corporate restructurings
Depending on the circumstances, board or shareholder approval may be required.
Transaction documentation should be consistent with the company's governing documents and applicable legal requirements.
Executive Oversight
Boards can play an important role in monitoring executive leadership.
Oversight may include:
Executive performance
Compensation
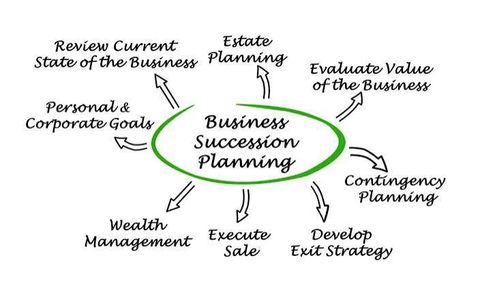
Succession planning
Strategic execution
Risk management
Compliance
Leadership development
Executive succession planning can be particularly important when a company depends heavily on a small number of senior leaders.
Governance in Family-Owned Businesses
Family-owned businesses may require governance structures that address both ownership and family relationships.
Potential considerations include:
Family ownership
Voting rights
Board composition
Family employment
Leadership succession
Compensation
Share transfers
Conflict resolution
Long-term ownership objectives
A clear governance structure can help separate family discussions from formal business decision-making.
Corporate Governance and Business Continuity
Governance can support continuity when unexpected events affect leadership or operations.
Organizations may establish procedures covering:
Interim leadership
Emergency decision-making
Board communications
Critical operations
Financial authority
Technology access
Succession
Crisis management
Business continuity plans should identify who has authority to make important decisions when normal management structures are disrupted.
Recent Developments
Corporate governance increasingly intersects with cybersecurity, artificial intelligence, sustainability reporting, data privacy, and technology oversight.
Boards may need to understand how technology-related risks affect:
Customer information
Financial reporting
Operational continuity
Intellectual property
Regulatory compliance
Third-party relationships
AI governance can also involve questions concerning data, security, accuracy, intellectual property, human oversight, and organizational accountability.
Governance expectations can change as laws, regulatory guidance, investor expectations, and technology risks develop.
Corporate Governance Planning Checklist
Organizations can periodically review:
Confirm the governing documents are current
Define board responsibilities
Maintain accurate ownership records
Schedule required meetings
Maintain board and shareholder minutes
Review director and officer responsibilities
Establish conflict-of-interest procedures
Review related-party transactions
Monitor financial controls
Review compliance requirements
Assess significant business risks
Review executive succession plans
Maintain appropriate corporate policies
Review cybersecurity and privacy oversight
Confirm required corporate filings
Review governance practices periodically
Tools and Resources
Useful corporate-governance resources can include:
Corporate bylaws
Articles of incorporation
Board charters
Committee charters
Board meeting calendars
Corporate minute books
Shareholder records
Governance policies
Conflict-of-interest disclosures
Risk registers
Compliance calendars
Financial reports
Internal-control documentation
Audit materials
Corporate filing records
Business continuity plans
Frequently Asked Questions
What is corporate governance?
Corporate governance is the framework used to direct, oversee, and hold an organization accountable. It establishes relationships and responsibilities among directors, officers, shareholders, management, and other stakeholders.
What does a board of directors do?
A board generally provides oversight of major strategic, financial, leadership, risk, and compliance matters. Exact responsibilities depend on the company structure, governing documents, and applicable law.
What are shareholder matters?
Shareholder matters can include voting rights, director elections, ownership records, distributions, share transfers, shareholder meetings, and approval of certain major corporate decisions.
Why are corporate records important?
Corporate records document important organizational decisions, ownership information, approvals, meetings, and governance activities. They can also support regulatory and legal compliance.
How often should corporate governance practices be reviewed?
There is no universal schedule. Organizations should review governance practices when laws change, ownership changes, leadership changes, significant transactions occur, or the company's risk profile evolves, as well as periodically as part of normal governance.
Conclusion
Corporate governance provides a framework for board oversight, shareholder matters, executive accountability, financial controls, compliance, and organizational risk management.
A well-structured governance framework can help clarify responsibilities, document important decisions, monitor significant risks, and align management activities with the organization's long-term objectives.
Governance requirements vary according to company structure, ownership, industry, jurisdiction, and applicable laws. Organizations should therefore periodically review their governing documents and obtain appropriately qualified professional guidance when significant legal, financial, regulatory, or ownership matters arise.
Related Post...