Employer Payroll Tax Guide: Filing Duties, Tax Records, and Business Planning
Employer payroll taxes are a central part of operating a business with employees. Employers may need to withhold taxes from employee wages, contribute employer-paid taxes, submit deposits, file federal returns, provide wage statements, and maintain accurate payroll records.
Payroll obligations can involve federal income-tax withholding, Social Security and Medicare taxes, federal unemployment tax, state payroll taxes, local requirements, and employment-related reporting. The exact duties depend on the business structure, employee classification, payroll amount, location, and applicable rules.
The IRS explains that employers are responsible for withholding, depositing, reporting, and paying employment taxes, even when payroll activities are handled by an outside payroll provider.
Main Types of Employer Payroll Taxes
Federal Income Tax Withholding
Employers generally withhold federal income tax from employee wages based on the employee’s Form W-4 and applicable IRS withholding procedures.
The amount withheld can vary according to:
Employee wages
Pay frequency
Form W-4 information
Filing status
Multiple-job adjustments
Additional withholding requests
Applicable IRS withholding tables
Federal income tax withheld from employee pay is not the employer’s own income tax. The employer generally holds and remits the amount according to federal deposit requirements.
Social Security and Medicare Taxes
Social Security and Medicare taxes are commonly referred to as FICA taxes.
In general:
Social Security tax includes an employee share and an employer share.
Medicare tax includes an employee share and an employer share.
Additional Medicare Tax may apply to certain employee wages above the applicable threshold.
Employer Social Security and Medicare contributions are separate from amounts withheld from employees.
The IRS states that employers must pay the employer share of Social Security and Medicare taxes in addition to withholding the employee share. <Cite ref="turn0search2" />
Federal Unemployment Tax
The Federal Unemployment Tax Act, commonly called FUTA, generally applies to the employer rather than the employee.
FUTA is reported on Form 940, Employer’s Annual Federal Unemployment Tax Return. FUTA tax is not normally deducted from employee wages.
State unemployment-tax obligations are separate and may apply according to state law, employer account status, employee wages, and other factors. <Cite refs={["turn0search5","turn0search7"]} />
Important Federal Payroll Tax Forms
Employers may use several federal forms depending on their payroll activities.
| Form | Main Purpose |
|---|---|
| Form 941 | Quarterly reporting of federal income tax withheld and Social Security and Medicare taxes |
| Form 940 | Annual federal unemployment tax reporting |
| Form W-2 | Reporting employee wages and tax information |
| Form W-3 | Transmitting Forms W-2 to the Social Security Administration |
| Form 943 | Annual reporting for certain agricultural employers |
| Form 944 | Annual employment-tax return for employers specifically instructed to use it |
| Form 945 | Reporting certain federal income-tax withholding from nonpayroll payments |
| Form 1099-NEC | Reporting qualifying nonemployee compensation |
Most employers subject to federal income-tax withholding or Social Security and Medicare taxes generally file Form 941 quarterly. Certain employers may instead file Form 944 if the IRS has notified them that they qualify for the annual filing program. <Cite refs={["turn0search2","turn0search5"]} />
Form 941 Filing Duties
Form 941 is the Employer’s Quarterly Federal Tax Return.
It generally reports:
Wages paid to employees
Federal income tax withheld
Employee Social Security tax
Employer Social Security tax
Employee Medicare tax
Employer Medicare tax
Additional Medicare Tax withheld
Certain payroll-tax adjustments
Applicable payroll-tax credits
The standard quarterly due dates are generally:
| Quarter | Period Covered | General Due Date |
|---|---|---|
| First quarter | January–March | April 30 |
| Second quarter | April–June | July 31 |
| Third quarter | July–September | October 31 |
| Fourth quarter | October–December | January 31 |
If a due date falls on a weekend or federal holiday, the applicable filing deadline may move to the next business day.
Employers should verify the current IRS instructions for the relevant tax year because filing rules, exceptions, and special circumstances can change. <Cite ref="turn0search2" />
Payroll Tax Deposits
Filing a payroll tax return and depositing payroll taxes are separate responsibilities.
Employers generally deposit:
Federal income tax withheld
Employee Social Security and Medicare taxes
Employer Social Security and Medicare taxes
FUTA tax when applicable
The deposit schedule may be monthly or semiweekly, depending on the employer’s payroll-tax liability during the IRS lookback period. Some small employers may qualify for different payment arrangements.
Federal employment-tax deposits generally must be made electronically. The IRS identifies EFTPS, business tax accounts, financial-institution ACH payments, same-day tax wires, and authorized third-party arrangements as possible payment methods. <Cite ref="turn0search6" />
Late deposits can lead to penalties and interest. Businesses should maintain evidence of every deposit, including:
Deposit date
Amount paid
Tax period
Payment method
Confirmation number
EFTPS record or other payment receipt
Person responsible for the transaction
Form W-2 and Year-End Reporting
Employers generally must prepare Form W-2 for employees who received reportable wages or other compensation.
Form W-2 reports information such as:
Total wages
Federal income tax withheld
Social Security wages
Social Security tax withheld
Medicare wages
Medicare tax withheld
Certain benefits
Retirement-plan information
State and local wage information where applicable
Form W-3 transmits Copy A of Forms W-2 to the Social Security Administration.
For the 2026 tax year, the IRS instructions state that Forms W-2 must generally be furnished to employees and filed with the Social Security Administration by January 31, 2027, subject to applicable weekend or holiday adjustments and permitted extensions. <Cite ref="turn0search4" />
Employers should reconcile Forms W-2 with:
Payroll registers
Form 941 filings
General-ledger payroll accounts
Tax deposits
Employee benefit records
State payroll reports
Differences between payroll records and year-end wage statements can create correction work and may lead to notices or penalties.
Employee Records and Payroll Documentation
Accurate payroll records help support tax filings, employee inquiries, audits, and internal financial reporting.
Important records may include:
Employer Identification Number
Employee names and addresses
Social Security numbers or other required identifiers
Dates of employment
Wage rates
Hours worked
Overtime records
Payroll registers
Bonus and commission records
Tip reports
Benefit deductions
Expense reimbursements
Forms W-4
Forms W-2 and W-2c
Payroll tax returns
Tax-deposit confirmations
Records of fringe benefits
Records supporting tax credits
Sick-leave or family-leave documentation where applicable
Payroll-provider reports
State and local tax filings
The IRS states that employment-tax records generally must be retained for at least four years after the fourth-quarter filing for the year. Certain records supporting specific tax credits may require longer retention. <Cite refs={["turn0search0","turn0search1"]} />
Payroll Tax Record Retention
A payroll retention policy should distinguish between general employment-tax records and records subject to longer legal or business requirements.
A basic retention schedule may look like this:
| Record Category | General Planning Consideration |
|---|---|
| Payroll registers | Retain according to IRS, labor, and business requirements |
| Forms W-4 | Maintain for the required employment-tax period |
| Forms 941 | Keep with supporting payroll and deposit records |
| Forms W-2 and W-3 | IRS instructions generally identify at least four years for employer copies |
| Tax-deposit confirmations | Retain with the related tax period |
| Employee benefit records | Review applicable tax, benefits, and employment rules |
| Payroll corrections | Keep original and corrected records together |
| Tax-credit documentation | Apply the specific credit’s retention requirement |
| Legal-hold records | Suspend routine deletion when preservation is required |
The four-year IRS employment-tax period is a baseline, not a universal rule for every payroll-related document. State wage laws, employee disputes, benefit-plan rules, tax examinations, contracts, litigation, and internal policies may require longer retention.
Payroll Providers and Employer Responsibility
A business may use a payroll provider, reporting agent, accountant, or payroll platform to assist with payroll processing.
An outside provider may help with:
Payroll calculations
Tax-form preparation
Tax deposits
Employee wage statements
Payroll reporting
Employee payment processing
Payroll record organization
However, outsourcing does not automatically remove the employer’s responsibility for accurate payroll information, timely filings, and tax compliance.
The IRS explains that employers remain responsible for employment-tax obligations even when a payroll provider performs payroll-related tasks. Employers should therefore confirm that deposits and filings are made under the correct employer identification number and retain access to supporting records. <Cite refs={["turn0search0","turn0search4"]} />
State and Local Payroll Requirements
Federal payroll compliance is only one part of the overall process.
Depending on the location, employers may also need to address:
State income-tax withholding
State unemployment insurance
Local wage taxes
Paid-leave programs
State new-hire reporting
Wage-payment statements
Disability or family-leave contributions
Workers’ compensation reporting
State payroll registration
Local business requirements
State and local rules can differ significantly. A business operating in multiple states may need separate registrations, withholding procedures, filing calendars, and employee-location controls.
Payroll systems should therefore capture the employee’s work location, residence where relevant, assigned tax jurisdiction, and applicable withholding rules.
Recent Updates and Planning Considerations
Payroll rules and filing instructions are updated periodically by the IRS, the Social Security Administration, state tax agencies, and other authorities.
For 2026 planning, employers should review:
Current IRS Publication 15
Current Form 941 instructions
Current Form 940 instructions
Current Forms W-2 and W-3 instructions
Applicable Social Security and Medicare wage limits
Additional Medicare Tax rules
Current electronic-filing thresholds
State unemployment-tax rates
State and local withholding rules
Payroll software tax-table updates
Changes affecting employee benefits or tax credits
The IRS states that employers filing 10 or more information returns, when the applicable information-return categories are combined under the relevant rules, generally must file electronically. Employers should confirm the current threshold and filing requirements before year-end reporting. <Cite ref="turn0search5" />
Payroll Compliance Planning Checklist
Businesses can use the following checklist when reviewing payroll-tax procedures:
| Area | Key Question |
|---|---|
| Employer registration | Is the correct EIN used for payroll filings? |
| Employee setup | Are Forms W-4 and required employee data maintained? |
| Classification | Are workers classified correctly under applicable rules? |
| Withholding | Are federal, state, and local taxes calculated correctly? |
| Deposits | Are payroll-tax deposits made on the required schedule? |
| Form 941 | Are quarterly returns accurate and timely? |
| Form 940 | Is FUTA reporting completed when required? |
| Year-end forms | Are Forms W-2 and W-3 reconciled and submitted on time? |
| Records | Are payroll and tax records retained appropriately? |
| Corrections | Is there a documented process for correcting payroll errors? |
| Provider oversight | Can the employer verify third-party filings and deposits? |
| Security | Are payroll records protected from unauthorized access? |
| Review | Are tax calendars and procedures reviewed regularly? |
Tools and Resources
Useful U.S. payroll-tax resources include:
IRS Publication 15, Employer’s Tax Guide: Explains withholding, deposits, reporting, and employment-tax recordkeeping.
IRS Employment Tax Recordkeeping: Provides information about required payroll records and general retention periods.
IRS Employment Tax Due Dates: Lists filing and deposit deadlines.
IRS Form 941 Instructions: Explains quarterly employment-tax reporting.
IRS Form 940 Resources: Provides federal unemployment-tax information.
IRS Forms W-2 and W-3 Instructions: Covers year-end wage reporting and transmittal requirements.
Social Security Administration: Provides employer wage-reporting resources and electronic filing information.
State tax and workforce agencies: Provide state-specific withholding, unemployment, and wage-reporting requirements.
Frequently Asked Questions
What are employer payroll taxes?
Employer payroll taxes are taxes connected with employee compensation. They can include employee tax withholding handled by the employer, employer-paid Social Security and Medicare taxes, FUTA, and state or local payroll obligations.
How often must employers file payroll tax returns?
Many employers file Form 941 quarterly. Some employers may qualify for annual Form 944 filing if the IRS has specifically notified them. Other forms, including Form 940 and Forms W-2 and W-3, follow different reporting schedules.
How long should payroll tax records be kept?
The IRS generally requires employment-tax records to be retained for at least four years after the fourth-quarter filing for the year. Certain tax-credit records and other documents may require longer retention.
Is an employer still responsible when using a payroll provider?
Yes. A payroll provider may perform calculations, filings, and deposits, but the employer should verify that information is accurate and that required obligations are completed under the correct employer identification number.
What is the difference between Form 941 and Form 940?
Form 941 generally reports federal income-tax withholding and Social Security and Medicare taxes on a quarterly basis. Form 940 reports federal unemployment tax annually.
Conclusion
Employer payroll tax compliance involves more than processing employee payments. Businesses must coordinate withholding, tax deposits, federal returns, wage statements, state requirements, record retention, security, and internal review.
A practical payroll-tax program should use a reliable filing calendar, accurate employee records, documented approval procedures, reconciliation between payroll and accounting records, and regular review of IRS and state guidance.
Because payroll requirements can vary by employer, worker classification, location, tax year, and business activity, organizations should confirm current rules with the IRS and applicable state authorities before making significant payroll or compliance decisions.

Related Post...
Management Consulting Guide: Business Strategy, Operational Improvement, and Planning
Updated: September 15, 2026
Read More
Recruitment Process Management Guide: Candidate Workflows, Screening, and HR Planning
Updated: September 15, 2026
Read More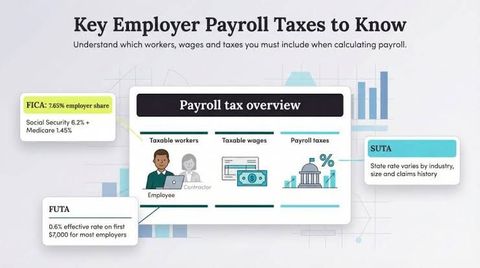
Employer Payroll Tax Guide: Filing Duties, Tax Records, and Business Planning
Updated: September 16, 2026
Read More