Business Due Diligence Guide: Financial Records, Legal Reviews, Risk Factors, and Acquisition Insights
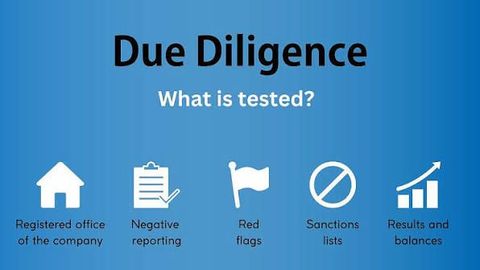
Business due diligence is the structured investigation performed before acquiring, investing in, or entering into a significant transaction involving a company.
The process helps a prospective buyer understand the target business beyond its marketing materials or initial financial presentation. It can involve reviewing financial records, contracts, tax information, employees, customers, intellectual property, assets, liabilities, regulatory requirements, technology, and potential risks.
The U.S. Small Business Administration recommends conducting thorough due diligence when evaluating an existing business and suggests reviewing areas such as contracts, leases, cash flow, inventory, licenses, permits, financial statements, tax returns, and transaction documents.
Due diligence does not eliminate acquisition risk. Even extensive investigations may fail to identify every liability, accounting irregularity, legal issue, cybersecurity problem, or operational weakness.
Why Business Due Diligence Matters
An acquisition can involve significant financial and operational commitments.
A structured due-diligence process can help a buyer:
Verify information provided by the seller
Understand historical financial performance
Identify existing liabilities
Review contractual obligations
Evaluate legal and regulatory exposure
Assess customer and supplier concentration
Examine operational dependencies
Identify technology and cybersecurity risks
Understand the target's assets and intellectual property
Evaluate potential integration challenges
Support valuation and transaction negotiations
The objective is not simply to find problems. It is to develop a more complete understanding of the business and determine whether the proposed transaction assumptions are supported by available evidence.
Financial Due Diligence
Financial review is usually one of the most important parts of business due diligence.
A buyer may examine:
Income statements
Balance sheets
Cash-flow statements
General ledgers
Accounts receivable
Accounts payable
Bank statements
Tax returns
Payroll records
Debt schedules
Capital expenditures
Inventory records
Customer revenue
Supplier expenses
Financial projections
SBA guidance recommends reviewing historical financial statements and using financial information to understand the existing business and its future financial outlook.
The review should focus not only on reported revenue and earnings but also on whether the underlying financial information is consistent, supported, and sustainable.
Quality of Earnings Review
A quality-of-earnings review examines whether reported earnings reasonably represent the business's ongoing economic performance.
Potential areas of review include:
Recurring versus non-recurring revenue
One-time expenses
Owner-related expenses
Unusual income
Related-party transactions
Changes in accounting practices
Customer concentration
Revenue recognition
Unusual working-capital movements
Deferred expenses
Exceptional events
For example, a business may show strong historical earnings because of a one-time transaction that is unlikely to recur. Identifying this distinction can affect valuation and future projections.
Tax Records and Obligations
Tax information can reveal liabilities or inconsistencies that may not be obvious from management accounts.
Depending on the transaction, a buyer may review:
Federal tax returns
State tax filings
Local tax records
Payroll-tax filings
Sales-tax filings
Property-tax records
Tax notices
Tax audits
Outstanding assessments
Tax payment history
Tax-related correspondence
The exact review depends on the business structure, location, industry, transaction structure, and applicable tax rules.
Tax liabilities can also differ depending on whether a transaction involves assets, equity interests, or another structure.
Legal Due Diligence
Legal review examines the rights, obligations, disputes, and liabilities associated with the target business.
Common areas include:
Organizational documents
Ownership records
Operating agreements
Corporate bylaws
Shareholder agreements
Material contracts
Customer agreements
Supplier agreements
Lease agreements
Loan agreements
Employment agreements
Intellectual-property documents
Litigation records
Regulatory correspondence
Insurance policies
The SBA recommends attorney involvement in reviewing acquisition agreements and ownership-transfer documents.
Legal review should identify obligations that could continue after closing or affect the buyer's ability to operate the business.
Contracts and Commercial Obligations
Contracts can be among the most important documents in an acquisition.
A buyer may examine:
Contract duration
Renewal provisions
Termination rights
Assignment restrictions
Change-of-control provisions
Pricing commitments
Minimum purchase obligations
Exclusivity clauses
Service-level obligations
Indemnification provisions
Guarantees
Penalties
Confidentiality requirements
A contract that cannot be transferred to the buyer without consent can create a significant transaction issue.
Important customer and supplier agreements should therefore be reviewed before the transaction structure is finalized.
Assets and Liabilities
Due diligence should establish what is actually being acquired and which liabilities may remain with the business or transfer under the transaction structure.
Assets may include:
Cash
Accounts receivable
Inventory
Equipment
Vehicles
Real estate
Software
Domain names
Trademarks
Patents
Customer lists
Other intellectual property
Potential liabilities may include:
Loans
Accounts payable
Tax obligations
Lease obligations
Employee-related liabilities
Litigation
Warranty obligations
Environmental liabilities
Contractual commitments
Regulatory penalties
A complete transaction review should clearly distinguish included assets, excluded assets, assumed liabilities, and retained liabilities.
Intellectual Property Review
Intellectual property can represent a significant portion of a company's value.
A review may include:
Trademarks
Patents
Copyrights
Trade secrets
Software
Domain names
Proprietary processes
Customer databases
Licensing agreements
The buyer should consider whether the business actually owns the intellectual property it relies upon and whether important rights are properly documented.
Third-party licenses should also be reviewed for transfer restrictions, expiration dates, and ongoing obligations.
Employee and Workforce Review
Employees can be central to the continuity of an acquired business.
Due diligence may consider:
Employee numbers
Key personnel
Compensation structures
Employment agreements
Benefits
Independent contractors
Payroll obligations
Leave obligations
Employee disputes
Non-compete or confidentiality provisions where applicable
Workforce concentration
Pending employment claims
A buyer should also identify whether critical knowledge is concentrated among a small number of employees.
Employee-related requirements vary by state and transaction structure, so qualified legal and HR professionals should review applicable requirements.
Customer and Revenue Concentration
Revenue concentration can create a material business risk.
A buyer may analyze:
Largest customers
Revenue by customer
Customer retention
Contract duration
Renewal rates
Customer acquisition trends
Churn
Geographic concentration
Product concentration
Customer dependency
If a large percentage of revenue comes from one customer, losing that customer after an acquisition could materially affect financial performance.
Customer concentration should therefore be considered alongside contracts, renewal history, relationship strength, and competitive conditions.
Supplier and Operational Risk
A business can also be highly dependent on particular suppliers, vendors, technology providers, or logistics partners.
Review areas may include:
Key suppliers
Supplier concentration
Contract terms
Lead times
Alternative suppliers
Pricing volatility
Inventory dependencies
Outsourced functions
Critical technology providers
Business continuity arrangements
A buyer should determine whether the business can continue operating if a critical supplier becomes unavailable.
Regulatory and Compliance Review
Regulatory requirements vary significantly by industry and location.
Depending on the business, due diligence may include:
Business licenses
Industry permits
Environmental requirements
Health and safety obligations
Data-protection requirements
Consumer-protection rules
Employment regulations
Financial regulations
Industry certifications
Government contracts
SBA guidance notes that buyers should investigate licenses, permits, zoning, and environmental concerns where relevant.
A regulatory issue may affect the ability to operate the business after closing, so unresolved compliance matters should be identified early.
Cybersecurity and Data Privacy
Modern due diligence increasingly includes technology and data risks.
A buyer may review:
Cybersecurity policies
Security incidents
Data breaches
Access controls
Backup procedures
Encryption
Software dependencies
Cloud systems
Customer-data practices
Privacy policies
Third-party technology providers
Regulatory notifications
Recent acquisition disclosures also highlight cybersecurity, data handling, and privacy risks as areas that may require attention during acquisition due diligence.
Technology risks can be particularly important when the target business depends heavily on customer data, software platforms, cloud infrastructure, or digital transactions.
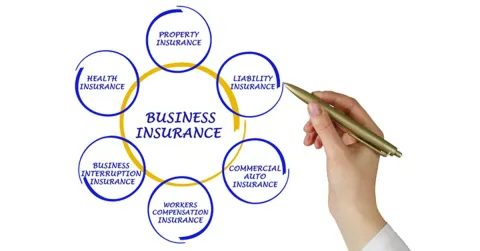
Insurance Review
Insurance records can help identify how the business manages risk.
Potential policies include:
General liability
Commercial property
Workers compensation
Professional liability
Cyber insurance
Commercial auto
Product liability
Directors and officers coverage
Business interruption coverage
A buyer should understand coverage limits, exclusions, claims history, deductibles, policy periods, and whether policies can continue or need to be replaced following a transaction.
Real Estate and Lease Review
If the business operates from leased or owned property, real-estate due diligence may be necessary.
Review areas can include:
Lease term
Renewal options
Rent provisions
Operating expenses
Assignment provisions
Change-of-control clauses
Zoning
Building condition
Environmental concerns
Property taxes
Insurance requirements
Permitted uses
A lease that cannot be transferred or renewed on acceptable terms could materially affect the transaction.
Valuation and Acquisition Analysis
Due diligence findings can influence how a buyer evaluates the transaction.
Common business valuation approaches include:
Income-based analysis
Cash-flow analysis
Market comparisons
Asset-based valuation
Adjusted earnings analysis
The SBA identifies several approaches to business valuation, including capitalized earnings, excess earnings, cash flow, tangible assets, and specific intangible assets.
Valuation should be based on appropriate financial information and assumptions rather than relying solely on the seller's asking price or historical revenue.
Acquisition Structure
The structure of the transaction can affect legal, tax, financial, and operational considerations.
Common structures include:
Asset acquisition
The buyer acquires specified business assets and may assume selected liabilities.
Equity acquisition
The buyer acquires ownership interests in the existing legal entity.
Merger
Two entities combine under an agreed transaction structure.
The appropriate structure depends on the parties, assets, liabilities, tax considerations, financing, regulatory requirements, and transaction objectives.
Legal and tax professionals should review the structure before the transaction is finalized.
Letter of Intent and Purchase Agreement
A letter of intent may establish preliminary transaction terms before detailed documentation is completed.
It may address:
Proposed purchase price
Transaction structure
Exclusivity
Confidentiality
Due-diligence period
Financing conditions
Closing conditions
Expected timeline
The final purchase agreement typically contains more detailed representations, warranties, conditions, covenants, indemnification provisions, and closing requirements.
The SBA identifies documents such as letters of intent, confidentiality agreements, contracts, leases, financial statements, tax returns, sales agreements, and purchase-price adjustments as relevant acquisition documents.
Due Diligence Red Flags
Potential warning signs can include:
Inconsistent financial statements
Unexplained revenue changes
Heavy customer concentration
Significant unpaid taxes
Undisclosed litigation
Unclear ownership of intellectual property
Expiring key contracts
Unresolved regulatory violations
Weak cybersecurity controls
Unusual related-party transactions
Excessive dependence on the owner
Incomplete corporate records
Unverified inventory
Large unexplained liabilities
Material supplier dependency
A red flag does not necessarily mean a transaction should be abandoned. It may indicate that additional investigation, transaction protections, price adjustments, or other conditions should be considered.
Due Diligence Checklist
Before completing an acquisition review, organizations can consider:
Review historical financial statements
Review tax returns and tax correspondence
Analyze revenue and customer concentration
Examine accounts receivable and accounts payable
Review debt and financing arrangements
Verify major assets and inventory
Review organizational documents
Examine material contracts
Review leases and property obligations
Investigate litigation
Review licenses and permits
Assess intellectual-property ownership
Review employee and payroll obligations
Examine insurance coverage and claims
Assess cybersecurity and privacy risks
Review supplier dependencies
Evaluate regulatory compliance
Assess business continuity
Compare valuation assumptions with evidence
Document unresolved issues before closing
Tools and Resources
Useful due-diligence resources can include:
Financial statements
General ledgers
Tax returns
Bank statements
Accounts-receivable aging reports
Accounts-payable aging reports
Customer and supplier contracts
Lease documents
Corporate records
Intellectual-property registrations
Insurance policies
Litigation records
Regulatory filings
Employee records
Inventory reports
Cybersecurity assessments
Business valuation models
Data-room platforms
Legal and accounting review checklists
The SBA provides acquisition guidance covering business valuation, financial records, contracts, tax returns, licenses, permits, and transaction documents.
Frequently Asked Questions
What is business due diligence?
Business due diligence is the structured review of a company before an acquisition, investment, or significant transaction. It can cover financial, legal, operational, tax, regulatory, technology, and commercial matters.
What financial records should be reviewed before buying a business?
Common records include financial statements, tax returns, bank statements, general ledgers, accounts-receivable and accounts-payable records, debt schedules, payroll records, inventory information, and financial projections.
What is legal due diligence in an acquisition?
Legal due diligence examines ownership, contracts, leases, litigation, intellectual property, employment matters, regulatory requirements, licenses, permits, and other legal obligations associated with the target.
What are common acquisition red flags?
Potential red flags include inconsistent financial information, undisclosed liabilities, significant customer concentration, unresolved litigation, weak internal controls, unclear intellectual-property ownership, expiring contracts, regulatory issues, and cybersecurity weaknesses.
Should an attorney and accountant be involved in due diligence?
For a significant acquisition, qualified legal and accounting professionals can help review transaction documents, financial information, tax matters, contracts, liabilities, and other specialized areas. The appropriate professionals depend on the transaction and jurisdiction.
Conclusion
Business due diligence provides a structured way to investigate a company before making a significant acquisition or investment decision.
A strong review combines financial records, tax information, legal documents, contracts, assets, liabilities, customers, suppliers, employees, intellectual property, technology, cybersecurity, insurance, and regulatory requirements.
The purpose is not simply to identify negative information. It is to compare the target's actual condition with the assumptions underlying the proposed transaction and identify issues that may require further investigation or transaction protections.
Because due diligence cannot guarantee that every problem will be discovered, buyers should combine document review with appropriate professional analysis, verification, valuation work, and transaction planning.
Related Post...