Surety Bond Guide: Bond Types, Underwriting Factors, and Business Requirements
Surety bonds are financial guarantee arrangements commonly used in construction, licensing, contracting, court proceedings, and other regulated business activities. A bond generally involves three parties: the principal, the obligee, and the surety.
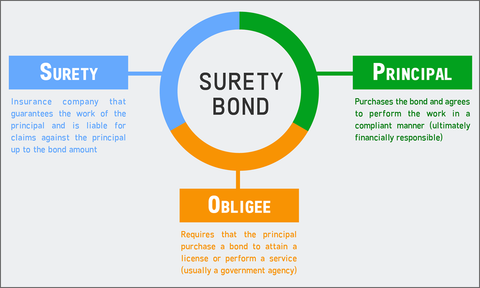
The principal is the party required to obtain the bond. The obligee is the party requiring the bond, such as a government agency, project owner, or other organization. The surety provides the guarantee that the principal will meet specified obligations under the bond.
Surety bonds can help establish financial and performance guarantees, but they are different from traditional insurance policies. Understanding the type of bond, underwriting requirements, and applicable regulations is important before entering into a bonded obligation.
How Surety Bonds Work
A typical surety arrangement involves three parties:
Principal: The business or individual responsible for fulfilling the underlying obligation.
Obligee: The party requiring the bond.
Surety: The company that guarantees the principal's obligations under the bond.
If the principal fails to meet a covered obligation, the obligee may make a claim against the bond according to its terms.
If the surety pays a valid claim, the principal may remain responsible for reimbursing the surety under the terms of the indemnity agreement.
Common Types of Surety Bonds
Contract Bonds
Contract bonds are frequently associated with construction and public projects.
Common examples include:
Bid bonds
Performance bonds
Payment bonds
Maintenance or warranty bonds
A performance bond can provide a guarantee concerning contractual performance, while a payment bond can address certain payment obligations associated with a project.
Commercial Surety Bonds
Commercial bonds can support various licensing, regulatory, and business obligations.
Examples may include:
License and permit bonds
Contractor license bonds
Public official bonds
Utility bonds
Fiduciary bonds
The exact requirements depend on the applicable government agency, contract, license, or regulation.
Court Bonds
Court-related surety bonds may be required in certain legal proceedings.
Examples can include:
Probate bonds
Appeal bonds
Injunction bonds
Fiduciary bonds
Requirements vary depending on the court, jurisdiction, and type of proceeding.
Customs Bonds
Businesses involved in importing goods into the United States may encounter customs bonds designed to guarantee certain obligations to U.S. Customs and Border Protection.
The applicable bond type and amount depend on the circumstances and relevant customs requirements.
Surety Bond vs. Insurance
Although both involve risk management, surety bonds and insurance generally operate differently.
With insurance, the insurer generally assumes covered risk in exchange for a premium. With a surety bond, the surety guarantees the principal's obligation to the obligee, while the principal generally remains responsible for fulfilling that obligation.
This distinction is important when evaluating contractual and financial responsibilities.
Surety Bond Underwriting Factors
Surety companies typically evaluate the applicant before issuing a bond. The underwriting process can vary significantly depending on the bond type, amount, industry, and applicant.
Common considerations can include:
Financial strength
Credit history
Business experience
Project history
Management experience
Existing obligations
Banking relationships
Working capital
Company financial statements
Operational capacity
Previous bond performance
For larger or more complex contract bonds, underwriting can involve a more detailed review of the company's financial and operational position.
The Three Cs of Surety Underwriting
Surety underwriting is often discussed using three broad categories: character, capacity, and capital.
Character can involve the experience, reputation, management history, and reliability of the business owners and management team.
Capacity concerns the organization's ability to perform the work or fulfill the underlying obligation.
Capital relates to financial strength, liquidity, working capital, and overall financial resources.
The relative importance of these factors can depend on the type and size of the requested bond.
Financial Statements and Documentation
Applicants for larger bonds may need to provide financial information to support underwriting.
Potential documentation can include:
Business financial statements
Bank information
Accounts receivable information
Accounts payable information
Work-in-progress schedules
Current contracts
Business tax records
Organizational information
Personal financial statements for owners when applicable
Accurate and current financial documentation can help underwriters evaluate the applicant's ability to meet its obligations.
Credit and Surety Bonds
Credit information can be an important underwriting factor, particularly for smaller commercial bonds and certain contract obligations.
A strong credit profile may support underwriting, while weaker credit can result in additional review, higher collateral requirements, reduced bonding capacity, or other conditions depending on the surety and bond type.
Credit is only one factor, however. Financial resources, experience, management, project history, and the specific characteristics of the obligation can also influence underwriting.
Bond Amount and Bonding Capacity
The amount of a surety bond represents the maximum financial guarantee specified by the bond.
For businesses that regularly pursue construction contracts, bonding capacity can be an important consideration. It refers broadly to the level of bonded work a surety is willing to support based on its assessment of the company's financial and operational capabilities.
Businesses seeking larger bonding capacity may need stronger financial records, established project experience, adequate working capital, and appropriate internal controls.
Indemnity Agreements
A surety may require the principal and, in some cases, related parties to sign an indemnity agreement.
An indemnity agreement can establish the principal's responsibility for certain losses, expenses, or claim payments incurred by the surety under the bond.
Businesses should understand these obligations before signing because the agreement can create significant financial responsibilities.
Surety Bond Business Requirements
Requirements vary by bond type and jurisdiction, but businesses may need to provide:
Legal business name
Business structure
Licensing information
Ownership information
Financial records
Credit information
Contract documentation
Project information
Bond amount
Obligee requirements
Previous bonding history
Some government or licensing authorities may prescribe specific bond forms, amounts, surety qualifications, or filing procedures.
How to Apply for a Surety Bond
A typical application process can involve several stages.
1. Identify the required bond
Determine the exact bond type, amount, obligee, and applicable requirements.
2. Gather documentation
Prepare financial, business, licensing, contractual, and ownership information relevant to underwriting.
3. Submit the application
The application is reviewed by the surety or an authorized intermediary.
4. Underwriting review
The surety evaluates financial strength, experience, credit, capacity, and other relevant factors.
5. Receive bond terms
If approved, the applicant receives the applicable premium, conditions, and documentation requirements.
6. Execute and file the bond
The completed bond is signed and submitted according to the obligee's requirements.
What Can Affect Surety Bond Approval?
Several factors may influence underwriting decisions:
Requested bond amount
Applicant's financial position
Credit history
Industry experience
Management experience
Previous contract performance
Existing bonded obligations
Project complexity
Contract terms
Claims history
Available working capital
A business that is financially sound but lacks relevant experience may receive a different underwriting assessment from an established contractor with a long project history.
U.S. Regulatory Considerations
Surety bond requirements in the United States can come from federal, state, and local laws, contracts, licensing rules, and government procurement requirements.
For federal construction contracts, the Miller Act establishes payment and performance bond requirements for certain federal public works contracts above specified thresholds.
State and local governments may impose their own bonding requirements for public projects, professional licensing, contractor registration, permits, and regulated activities.
Businesses should verify the exact requirements imposed by the relevant obligee rather than assuming that one bond form or amount applies nationwide.
Recent Business Planning Considerations
Businesses using surety bonds should periodically review their bonding needs as operations change.
Important triggers for a review can include:
Larger projects
New geographic markets
Changes in ownership
New business activities
Increased contract volume
Changes in financial position
New licensing requirements
Additional government contracts
Maintaining organized financial records and project documentation can also make future underwriting reviews more straightforward.
Tools and Resources
Businesses researching surety requirements can consult:
U.S. Small Business Administration: Federal contracting and small-business resources can help businesses understand government procurement requirements.
U.S. Department of Transportation: Federal contracting resources may be relevant for businesses working on transportation-related projects.
U.S. government procurement resources: Federal contracting requirements can include specific bonding provisions.
State licensing agencies: State agencies can identify licensing and bond requirements for regulated businesses and contractors.
Contract documents: The obligee's contract or licensing documentation should be reviewed to identify the required bond form and amount.
Financial records: Current financial statements and project schedules can support underwriting preparation.
FAQs
What is a surety bond?
A surety bond is a guarantee involving a principal, an obligee, and a surety. It generally guarantees that the principal will fulfill a specified obligation.
Is a surety bond the same as insurance?
No. Although both involve risk management, a surety bond generally guarantees the principal's obligation to the obligee, while insurance generally transfers covered risk to an insurer.
What factors do surety companies consider?
Underwriting can consider financial strength, credit, experience, management, project history, capacity, existing obligations, and the requested bond amount.
Can a business with weaker credit obtain a surety bond?
Possibly. Underwriting decisions vary by surety, bond type, amount, and the applicant's overall financial and operational profile. Additional conditions or documentation may apply.
Why is bonding capacity important for contractors?
Bonding capacity can influence the size and volume of contracts a surety is willing to support. Financial strength, working capital, experience, and project performance can all affect that capacity.
Conclusion
Surety bonds can play an important role in construction, government contracting, licensing, court proceedings, and other regulated business activities. Understanding the distinction between bond types and insurance, preparing accurate financial information, and maintaining strong project records can help businesses approach the underwriting process more effectively.
Because bond requirements vary by contract, industry, obligee, and jurisdiction, businesses should verify the applicable requirements before entering into a bonded obligation.

Related Post...
Commercial Litigation Funding Guide: Case Financing, Legal Costs, and Funding Structures
Updated: September 14, 2026
Read More
Cargo Insurance Guide: Freight Protection, Shipping Risks, and Claims Information
Updated: September 14, 2026
Read More
Marine Insurance Guide: Vessel Coverage, Shipping Risks, and Policy Planning
Updated: September 14, 2026
Read More