Family Asset Planning Guide: Ownership Decisions, Estate Documents, Wealth Transfer, and Legal Insights
Family asset planning is the process of organizing property, financial accounts, business interests, and other assets to clarify ownership, support long-term financial goals, and prepare for future transfers.
Family assets may include real estate, investment accounts, retirement accounts, business interests, insurance proceeds, personal property, and other financial holdings.
Effective planning can help families understand who owns particular assets, who may receive them later, which documents control their transfer, and what administrative or tax considerations may apply.
Because ownership and inheritance rules vary by jurisdiction and individual circumstances, significant decisions should be reviewed with appropriately qualified professionals.
Why Family Asset Planning Matters
Families may have assets spread across multiple accounts, properties, entities, and financial institutions.
Without organized planning, families may encounter:
Unclear ownership
Outdated beneficiary designations
Conflicting estate documents
Difficult asset transfers
Family disagreements
Probate complications
Business succession issues
Tax-reporting questions
Incomplete financial records
Problems locating important documents
A coordinated plan can help connect ownership decisions with estate documents and long-term wealth-transfer objectives.
Types of Family Assets
Family asset planning can involve many different forms of property.
Common categories include:
Primary residences
Investment real estate
Bank accounts
Brokerage accounts
Retirement accounts
Life insurance
Business interests
Family partnerships
Trust assets
Vehicles
Valuable personal property
Intellectual property
Digital assets
Collectibles
Each asset can have different ownership, transfer, tax, and documentation considerations.
For example, a retirement account may use a beneficiary designation, while real estate may transfer through a deed, trust, probate process, or another legal arrangement.
Ownership Decisions
Ownership structure is an important part of family asset planning.
Potential ownership arrangements can include:
Individual ownership
Joint ownership
Tenancy arrangements
Trust ownership
Business-entity ownership
Partnership interests
Community-property arrangements in applicable jurisdictions
The appropriate structure depends on the asset, family circumstances, jurisdiction, financial objectives, and applicable law.
Changing ownership simply to achieve a perceived tax or estate benefit can create other consequences. Ownership changes should therefore be reviewed before implementation.
Estate Documents
Several documents can play important roles in family asset planning.
Common documents include:
Will
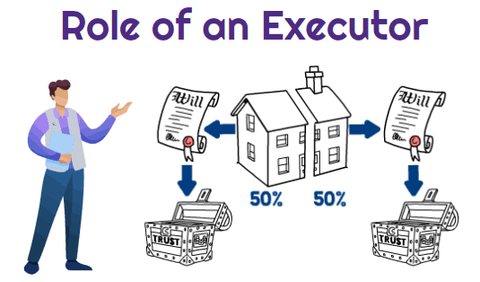
A will provides instructions concerning certain assets and may nominate an executor or personal representative. Assets governed by beneficiary designations, joint ownership, or certain trusts may be handled differently.
Revocable Living Trust
A revocable living trust can hold assets during an individual's lifetime and may provide instructions for management and distribution according to the trust document.
Durable Power of Attorney
A financial power of attorney can authorize an appointed individual to handle certain financial matters when the document and applicable law permit.
Healthcare Documents
Healthcare directives and related documents can address medical decision-making rather than direct ownership of financial assets.
Beneficiary Designations
Retirement accounts, insurance policies, and certain financial accounts may allow individuals to designate beneficiaries directly.
These documents should be coordinated so that their instructions do not unintentionally conflict.
Beneficiary Designations
Beneficiary designations can be particularly important because some assets may transfer according to the account's beneficiary instructions rather than through a will.
Families should periodically review:
Primary beneficiaries
Contingent beneficiaries
Beneficiary percentages
Changes in family circumstances
Account ownership
Policy ownership
Retirement-account beneficiaries
Insurance beneficiaries
Major life events such as marriage, divorce, birth, adoption, or death may create a reason to review beneficiary information.
An estate document cannot necessarily override an existing beneficiary designation. The controlling rules depend on the asset and applicable law.
Trusts and Family Assets
Trusts can be used in various estate-planning structures.
Depending on the type of trust, a trust may address:
Asset management
Distribution instructions
Beneficiary interests
Incapacity planning
Privacy considerations
Family succession
Charitable objectives
Certain estate-planning goals
A trust does not automatically produce the same legal or tax outcome in every situation.
Families should understand the specific trust terms, ownership arrangements, trustee responsibilities, and applicable tax rules before transferring assets into or relying on a trust.
Real Estate Planning
Real estate can represent a significant portion of family wealth.
Planning considerations may include:
Current ownership
Deeds
Mortgage obligations
Property taxes
Insurance
Rental income
Property management
Joint ownership
Trust ownership
Intended future recipients
Potential sale or transfer
Families with multiple properties may benefit from maintaining a centralized property record showing ownership, documentation, financial obligations, and planning objectives.
Real estate transfers may also have recording, tax, financing, or legal consequences.
Family Business Assets
Business interests can require additional planning.
Relevant documents may include:
Operating agreements
Shareholder agreements
Partnership agreements
Buy-sell agreements
Business valuation records
Ownership certificates
Succession plans
Financing documents
A family business plan can identify who may receive ownership interests and how management or ownership transitions should be handled.
Ownership transfer restrictions in governing agreements should be reviewed before making estate or succession decisions involving a business.
Wealth Transfer Strategies
Wealth transfer planning focuses on how assets may move between family members or other intended recipients.
Possible mechanisms can include:
Lifetime gifts
Inheritances
Trust arrangements
Beneficiary designations
Joint ownership
Business succession structures
Charitable transfers
Insurance arrangements
The appropriate strategy depends on the asset, family objectives, applicable tax rules, and legal structure.
Tax rules concerning gifts, estates, trusts, and inherited assets can change over time, making current professional guidance important.
Family Asset Inventory
An asset inventory can make estate and wealth-transfer planning more organized.
A useful inventory may record:
| Asset Category | Ownership | Institution/Location | Key Document | Beneficiary/Recipient |
|---|---|---|---|---|
| Real estate | Individual/joint/trust | Property records | Deed | As documented |
| Investment account | Individual/joint | Brokerage | Account statement | As designated |
| Retirement account | Individual | Financial institution | Account records | As designated |
| Business interest | Individual/entity | Business records | Agreement | As planned |
| Insurance | Policy owner | Insurer | Policy document | As designated |
The inventory should be updated when ownership, account information, beneficiaries, or family circumstances change.
Tax Considerations
Family asset planning can involve several tax concepts.
Depending on circumstances, these may include:
Federal estate taxes
Federal gift taxes
State estate taxes
State inheritance taxes
Income taxes
Capital gains
Trust taxation
Property taxes
Retirement-account taxation
Not every asset or family is subject to every type of tax.
Tax treatment can also depend on ownership, timing, asset basis, beneficiary status, trust structure, and applicable federal and state rules.
Families should use current tax information rather than relying on outdated thresholds or general assumptions.
Digital Assets
Digital property is increasingly relevant to family asset planning.
Examples include:
Online financial accounts
Digital photographs
Cloud storage
Websites
Domain names
Digital intellectual property
Cryptocurrency or other digital assets
Online business accounts
Electronic records
Families should consider documenting the existence and location of important digital assets while respecting applicable privacy and account-access requirements.
Passwords alone may not establish legal authority to access an account after death.
Family Communication
Asset planning is not only about documents. Communication can also reduce uncertainty.
Families may consider discussing:
General planning objectives
Location of important documents
Individuals responsible for administration
Business succession intentions
Property-management arrangements
Important financial relationships
Digital-asset information
Emergency contacts
The level of information shared should reflect family circumstances and appropriate privacy considerations.
Common Family Asset Planning Mistakes
Common planning problems can include:
Failing to update beneficiaries
Keeping outdated wills
Holding assets under unclear ownership
Ignoring business agreements
Failing to document digital assets
Mixing personal and trust assets
Making undocumented transfers
Assuming every asset passes through probate
Relying on outdated tax information
Failing to coordinate estate documents
Periodic review can help identify inconsistencies before they become administrative problems.
Recent Developments in Estate and Asset Planning
Family asset planning continues to evolve as households hold increasingly diverse assets.
Important developments include:
Greater attention to digital assets
Increased use of electronic records
Online estate-document organization
More complex business ownership structures
Growing interest in family governance
Greater attention to beneficiary coordination
Continued changes in federal and state tax rules
Technology-assisted financial organization
Families with substantial or complex assets may need to coordinate attorneys, accountants, financial professionals, insurance professionals, and business advisors.
Family Asset Planning Checklist
Families reviewing their asset-planning arrangements can consider:
Create an updated asset inventory
Confirm ownership of major assets
Locate current estate documents
Review beneficiary designations
Review trust arrangements
Check real estate records
Review business ownership documents
Organize financial records
Document important digital assets
Review insurance and retirement beneficiaries
Identify potential tax considerations
Consider family succession objectives
Review powers of attorney
Identify responsible administrative contacts
Schedule periodic plan reviews
Tools and Resources
Useful planning resources can include:
Estate-document files
Asset inventories
Beneficiary-designation records
Property records
Trust documents
Business agreements
Financial statements
Insurance policies
Retirement-account records
Tax records
Digital-asset inventories
Secure document-storage systems
Government tax resources
Estate-planning professionals
Government and legal requirements should always be checked against the jurisdiction applicable to the family and assets.
Frequently Asked Questions
What is family asset planning?
Family asset planning is the process of organizing ownership, estate documents, beneficiary information, financial records, and potential asset transfers to support long-term family objectives.
Why are beneficiary designations important?
Certain financial accounts and insurance policies may transfer according to beneficiary designations. Keeping those designations current can help ensure that account instructions reflect the individual's current intentions.
Should families create an asset inventory?
An asset inventory can help identify property, ownership arrangements, financial institutions, important documents, and intended recipients. It can also make later estate administration more organized.
Can a trust replace a will?
Not necessarily. A trust and a will can have different functions, and the appropriate documents depend on the individual's assets, objectives, and jurisdiction. Some estate plans use both.
How often should family asset plans be reviewed?
There is no universal schedule, but plans should generally be reviewed after significant life, financial, ownership, or legal changes and periodically to identify outdated information.
Conclusion
Family asset planning brings together ownership decisions, estate documents, beneficiary designations, financial records, trusts, property, business interests, and wealth-transfer objectives.
A coordinated plan can help families understand what they own, how assets are controlled, and what may happen to those assets in the future.
Because estate, tax, trust, and property rules vary by jurisdiction and circumstances, significant planning decisions should be based on current information and appropriate professional guidance.
Related Post...