Commercial Drone Insurance Guide: Coverage Types, Aviation Risks, and Business Planning
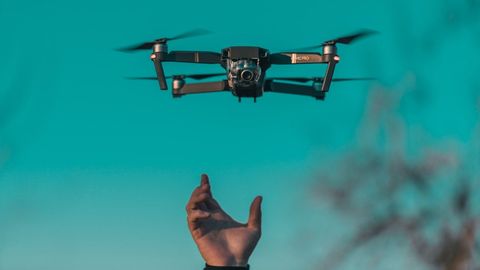
Commercial drones, also known as unmanned aircraft systems (UAS), are used across industries including aerial photography, construction, real estate, infrastructure inspection, agriculture, mapping, surveying, energy, utilities, and public safety.
As drone operations become more sophisticated, businesses must consider aviation-related risks in addition to ordinary business risks.
A drone can be damaged during flight, collide with property, injure a person, interfere with another aircraft, or create privacy and data-related concerns. Insurance planning can help a business understand which risks may be transferred through an appropriate policy and which remain the responsibility of the operator.
The FAA notes that businesses should examine their insurance policies carefully because ordinary business policies may exclude drone-related risks. Aviation-specific liability coverage is used by many drone operators.
Why Commercial Drone Insurance Matters
Commercial drone operations can involve several different exposure areas.
Important considerations include:
Damage to the aircraft
Damage to cameras, sensors, and other payloads
Bodily injury to third parties
Property damage
Aviation liability
Equipment transportation
Data and privacy concerns
Employee or contractor activities
Regulatory compliance
Accidents involving people or other aircraft
Legal defense and claims administration
The appropriate insurance structure depends on the type of drone, operation, aircraft value, operating environment, pilot qualifications, business structure, and policy wording.
Insurance should therefore be evaluated together with an organization's broader aviation risk-management plan.
Major Commercial Drone Insurance Coverage Types
Drone insurance policies can contain several different coverage components.
Drone Liability Insurance
Drone liability coverage generally addresses certain claims involving bodily injury or property damage arising from covered drone operations.
For example, a drone could accidentally strike a structure, vehicle, or other property.
Liability coverage can be particularly important when operations take place around construction sites, commercial properties, events, infrastructure, or populated areas.
Policy limits, exclusions, deductibles, territorial restrictions, and operational conditions should be reviewed carefully.
Drone Hull Insurance
Hull coverage is designed to address physical damage to the drone itself when the loss falls within the policy terms.
Potential risks may include:
Collision
Hard landing
Accidental damage
Certain weather-related incidents
Equipment damage during covered operations
Loss of the aircraft under specified circumstances
Hull coverage is separate from third-party liability coverage. A policy that protects against liability claims does not necessarily protect the aircraft itself.
Payload and Equipment Coverage
Commercial drones may carry expensive cameras, thermal sensors, LiDAR equipment, multispectral sensors, GPS equipment, or other specialized technology.
Businesses should determine whether the policy covers:
Cameras
Gimbals
Sensors
Payload equipment
Controllers
Batteries
Ground equipment
Portable data-storage equipment
Other aviation-related equipment
Coverage may depend on whether equipment is permanently installed, temporarily attached, transported, or used away from the aircraft.
Non-Owned Drone Coverage
Some businesses operate drones that they do not own.
For example, an organization may lease equipment or use aircraft belonging to another company.
Non-owned aircraft coverage may be relevant in these circumstances, depending on the policy structure and contractual arrangements.
Commercial General Liability Considerations
Businesses sometimes assume that a commercial general liability policy automatically covers drone operations.
That assumption can be incorrect.
The FAA specifically notes that many insurance products exclude risks associated with drone use, which is why operators should review policy language and consider aviation-specific coverage where appropriate.
Common Aviation Risks for Commercial Drone Operators
Drone insurance planning should begin with an understanding of operational risks.
Collision Risk
A drone may collide with:
Buildings
Utility structures
Trees
Vehicles
Other aircraft
Construction equipment
People
Obstacles
Risk increases when operations take place in congested environments or near structures.
Equipment Failure
Battery problems, navigation errors, communication interruptions, sensor failures, software issues, or mechanical problems can affect flight operations.
Maintenance records, preflight procedures, pilot training, and manufacturer instructions can reduce operational risk.
Weather Risk
Wind, rain, temperature extremes, visibility limitations, and other weather conditions can affect drone performance.
A commercial operation should establish appropriate weather limits based on aircraft specifications, operating conditions, and applicable aviation requirements.
Airspace Risk
Commercial operators must understand the airspace in which they intend to operate.
Part 107 establishes operating requirements for small UAS, including restrictions and safety requirements for commercial operations. The FAA's current Part 107 guidance covers small UAS weighing less than 55 pounds and includes requirements involving aircraft avoidance, visual line of sight, operations over people, and other operational matters.
Privacy and Data Risk
Drones can collect photographs, video, thermal information, mapping data, and other sensitive information.
Organizations should consider:
Data-storage practices
Access controls
Privacy policies
Cybersecurity safeguards
Data retention
Client confidentiality
Applicable privacy requirements
Insurance may not cover every privacy or cybersecurity exposure, so these risks should be reviewed separately.
FAA Requirements and Commercial Drone Operations
In the United States, many commercial drone operations involving small UAS fall under 14 CFR Part 107.
A remote pilot operating under Part 107 generally needs an FAA Remote Pilot Certificate. The FAA states that pilots must complete recurrent training every 24 calendar months to maintain aeronautical knowledge recency.
Drone registration is also relevant. The FAA states that Part 107 registration is required for applicable drones and currently lists a $5 registration fee per drone, with registration valid for three years.
Insurance does not replace regulatory compliance. A policy may provide financial protection for certain covered events, but it does not authorize an operation that violates FAA rules.
Remote ID and Insurance Planning
Remote Identification, or Remote ID, is an important part of the U.S. drone regulatory framework.
The FAA states that drones required to be registered must generally operate in accordance with Remote ID requirements. Standard Remote ID aircraft and broadcast modules transmit identification and location information during flight.
Operators should maintain records showing that their aircraft and operating procedures meet applicable requirements.
Remote ID compliance can also become part of broader operational risk management because regulators, law enforcement, and other authorized parties can use Remote ID information to identify an aircraft and locate its control station in certain circumstances.
Airspace Authorizations and Waivers
Some drone operations require additional FAA authorization.
For controlled airspace, Part 107 operators can use LAANC or the FAA's applicable authorization processes. The FAA explains that LAANC can provide authorization for eligible operations within controlled airspace.
Certain operations outside standard Part 107 limitations may require a waiver.
A waiver is an official FAA authorization allowing specific deviations from applicable Part 107 requirements when the operator demonstrates an acceptable safety approach.
Businesses should maintain documentation for relevant authorizations, waivers, pilot credentials, aircraft registrations, and operational procedures.
How Insurance Underwriting Can Consider Drone Operations
Insurance underwriting may consider several characteristics of a drone operation.
These can include:
Aircraft type
Aircraft value
Payload equipment
Pilot experience
Pilot certification
Flight hours
Geographic operating area
Airspace classification
Maximum operating altitude
Night operations
Operations over people
Operations near airports
Construction-site operations
Inspection activities
Mapping activities
Agricultural operations
Event operations
Package transportation
Safety procedures
Maintenance practices
Claims history
Higher-risk operations may require different policy structures, limits, exclusions, or underwriting conditions.
Commercial Drone Insurance Limits
Liability limits are an important part of insurance planning.
A business may evaluate limits based on:
Potential third-party injury exposure
Property values near operating areas
Contractual requirements
Project requirements
Aircraft characteristics
Client requirements
Regulatory considerations
Business risk tolerance
A higher liability limit does not necessarily mean every potential claim is covered. The policy's definitions, exclusions, conditions, and endorsements remain important.
Additional Insured and Certificate Requirements
Commercial clients, property owners, contractors, and government organizations may require evidence of insurance before allowing drone operations.
Businesses may encounter requests involving:
Certificates of insurance
Additional insured status
Waiver of subrogation
Primary and noncontributory wording
Specific liability limits
Project-specific requirements
These requirements vary by contract and jurisdiction.
The actual policy language should be reviewed rather than relying solely on a certificate.
Drone Insurance and Business Planning
Insurance is only one component of a broader commercial drone risk strategy.
A business plan can include:
| Planning Area | Key Consideration |
|---|---|
| Aircraft | Registration, maintenance, inspection, and configuration |
| Pilots | Certification, training, and operational experience |
| Airspace | Authorization and operating restrictions |
| Safety | Preflight, flight, and emergency procedures |
| Insurance | Liability, hull, equipment, and other applicable coverage |
| Contracts | Risk allocation and insurance requirements |
| Data | Storage, security, privacy, and access |
| Documentation | Flight records, maintenance records, and incident reports |
| Emergency planning | Lost-link, crash, weather, and other contingencies |
| Compliance | FAA and applicable state or local requirements |
This approach helps businesses evaluate insurance as part of an overall risk-management framework rather than as an isolated financial product.
Commercial Drone Claims and Incident Documentation
If an incident occurs, accurate documentation can become important.
A business should have procedures for recording:
Date and time
Flight location
Pilot identity
Aircraft identification
Registration information
Weather conditions
Flight purpose
Flight records
Photographs or video
Damage information
Witness information
Relevant FAA authorization
Maintenance history
Incident sequence
The appropriate notification process depends on the policy and the circumstances.
Businesses should follow their policy's reporting requirements and preserve relevant evidence.
Tools and Resources
Businesses evaluating commercial drone risk can use several categories of resources.
FAA DroneZone: Used for applicable drone registration and related FAA processes.
LAANC: Helps eligible Part 107 operators obtain certain controlled-airspace authorizations.
Remote ID resources: Help operators understand applicable identification requirements.
Flight-planning tools: Can help evaluate airspace, weather, terrain, and operational conditions.
Maintenance records: Document inspections, repairs, battery condition, and aircraft history.
Pilot records: Document certifications, training, and operational qualifications.
Incident forms: Provide a structured method for recording flight events.
Insurance policy documents: Define applicable limits, exclusions, conditions, and covered operations.
Contract records: Identify insurance and risk-allocation requirements imposed by clients or project partners.
Commercial Drone Insurance Planning Checklist
Before establishing an insurance and risk-management program, consider:
Identify every drone used in business operations
Document aircraft values and configurations
Identify cameras and specialized payloads
Confirm applicable FAA registration
Review Remote ID requirements
Verify pilot certification requirements
Document operating locations
Identify controlled-airspace operations
Review operations over people
Assess night-flight activities
Identify construction, inspection, mapping, or agricultural activities
Review existing business policy exclusions
Evaluate aviation liability coverage
Evaluate drone hull coverage
Review payload and equipment coverage
Consider non-owned aircraft exposure
Review contractual insurance requirements
Establish incident-reporting procedures
Maintain maintenance and flight records
Review policy exclusions and operational limitations
FAQs
Is commercial drone insurance required by the FAA?
FAA Part 107 establishes many requirements for commercial small-UAS operations, but federal drone operating rules should not be confused with an across-the-board federal insurance mandate. Insurance requirements can instead arise from contracts, clients, property owners, project requirements, lenders, or other circumstances. Operators should verify the requirements applicable to their specific operation.
What does commercial drone liability insurance cover?
Depending on the policy, drone liability insurance can address certain covered claims involving bodily injury or property damage arising from drone operations. Coverage limits and exclusions vary, so the actual policy wording should be reviewed.
What is drone hull insurance?
Drone hull insurance generally addresses physical damage to the aircraft itself when the loss falls within the policy terms. It is different from third-party liability coverage.
Does general business insurance cover drone operations?
Not necessarily. The FAA notes that many insurance products exclude drone-related risks, so businesses should review existing policies carefully and determine whether aviation-specific coverage is appropriate.
Does Part 107 apply to commercial drone operations?
Part 107 covers many small-UAS operations in the United States, including commercial operations involving aircraft weighing less than 55 pounds. Specific operating requirements depend on the circumstances.
Conclusion
Commercial drone insurance is an important part of risk planning for businesses operating unmanned aircraft.
The appropriate approach can involve several layers, including drone liability insurance, hull coverage, payload protection, non-owned aircraft considerations, contractual requirements, and broader aviation risk management.
Regulatory compliance is equally important. Commercial operators should understand Part 107, applicable registration requirements, Remote ID, airspace authorizations, pilot certification, and any applicable waivers.
A well-structured risk program combines appropriate insurance analysis with pilot training, aircraft maintenance, operational procedures, data protection, documentation, and regulatory compliance.

Related Post...
Long-Term Care Planning Guide: Senior Support, Care Options, and Financial Planning
Updated: September 08, 2026
Read More
Credit Monitoring Guide: Credit Reports, Identity Alerts, and Financial Protection
Updated: September 14, 2026
Read More
Marine Insurance Guide: Vessel Coverage, Shipping Risks, and Policy Planning
Updated: September 14, 2026
Read More